U.S. Companies Commit $2 Billion to Korea’s Semiconductor and Energy Supply Chain
Air Products, Axcelis, Corning and Pacifico Energy Expand Investment Across Chips, Materials and Power
🏭 iAtlas Daily #49 | Semiconductor Supply Chain & Energy | September 2026
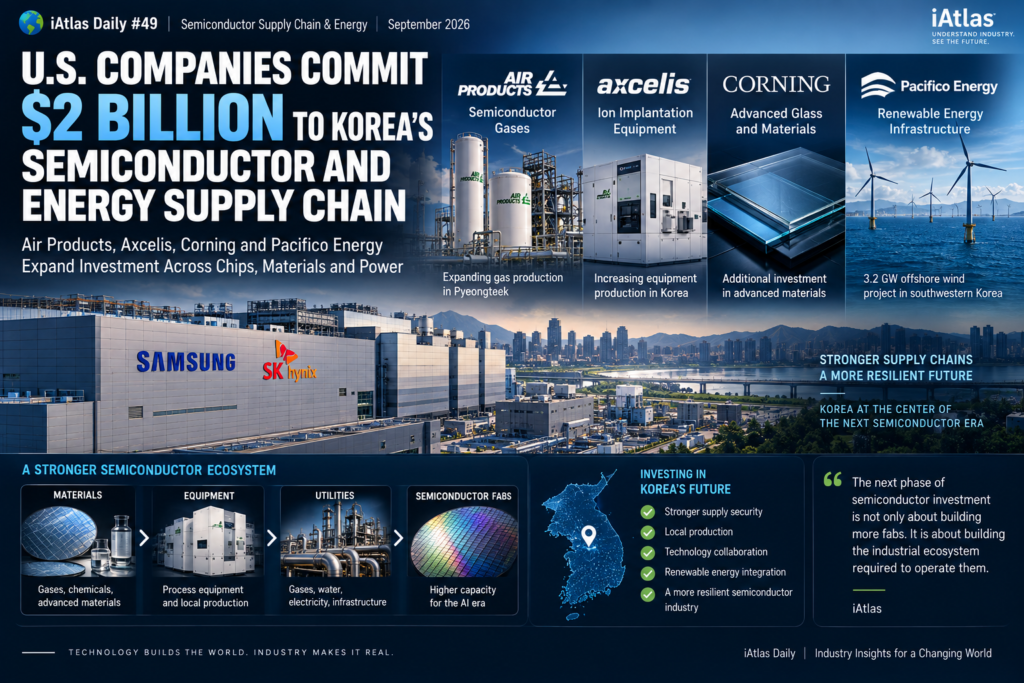
The U.S. Investment in Korea Semiconductor Industry is expanding beyond chip manufacturing itself.
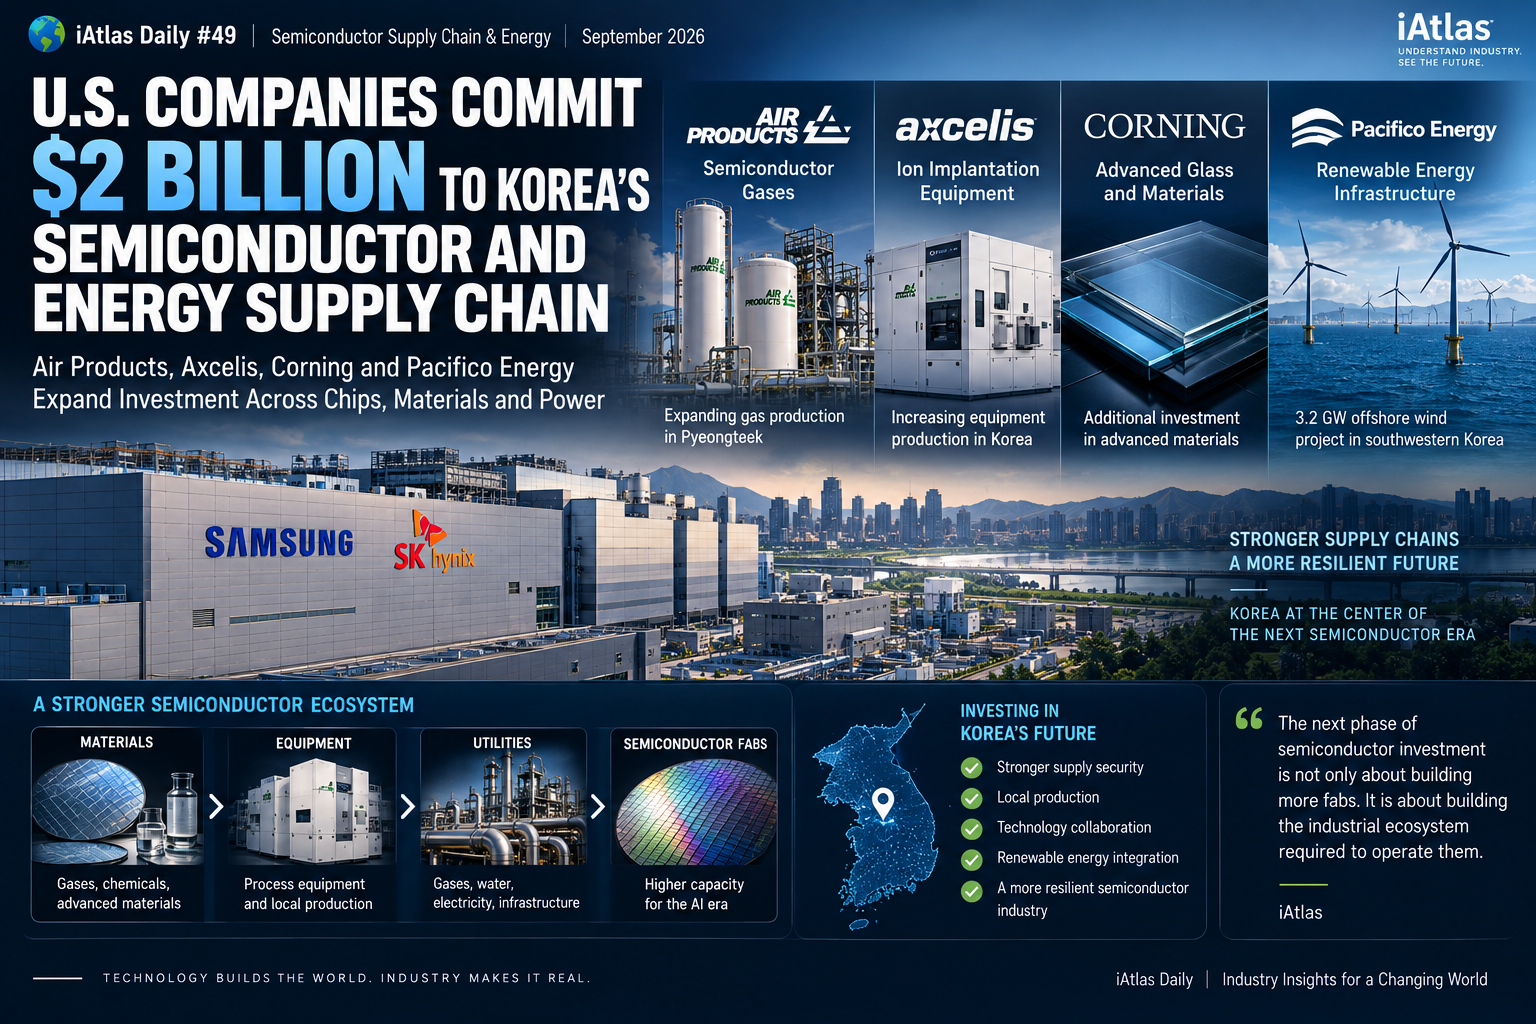
Four U.S. companies — Air Products, Axcelis Technologies, Corning and Pacifico Energy — have committed a combined $2 billion, or approximately KRW 2.8 trillion, in new investment in South Korea.
The projects span semiconductor gases, ion implantation equipment, advanced glass and materials, and offshore wind power.
At first glance, these investments appear to belong to different industries.
But together they reveal something larger.
As Samsung Electronics, SK hynix and Korea’s broader semiconductor ecosystem expand production for the AI era, the infrastructure surrounding semiconductor fabs must expand with them.
That includes:
Materials -> Process Equipment -> Industrial Gases -> Electricity ->
Semiconductor Manufacturing
The next phase of semiconductor investment is not only about building more fabs. It is about building the industrial ecosystem required to operate them.
🏭 The Big Story
South Korea’s Ministry of Trade, Industry and Resources announced the investment commitments following a ceremony in Washington on September 3 U.S. time.
The four companies represent very different parts of the industrial supply chain:
Air Products
Semiconductor industrial and specialty gases
Axcelis Technologies
Ion implantation equipment
Corning
Advanced glass and materials
Pacifico Energy
Renewable-energy infrastructure
Combined investment:
$2 Billion / KRW 2.8 Trillion
The important point is where those investments sit in the semiconductor ecosystem.
They are not primarily investments in chip design.
They support the physical manufacturing environment surrounding semiconductor production.
🧪 1. Air Products Is Expanding Semiconductor Gas Capacity
Air Products plans to expand its semiconductor-related gas production infrastructure in Pyeongtaek, one of Korea’s most important semiconductor manufacturing regions.
Industrial and specialty gases are essential inputs in semiconductor manufacturing.
Different processes require gases for:
- deposition
- etching
- cleaning
- chamber conditioning
- oxidation
- inert environments
- process control
A semiconductor fab therefore depends on a continuous supply of extremely high-purity gases.
The basic relationship is:
More Semiconductor Capacity -> More Process Equipment ->
More Gas Consumption -> More Local Gas Infrastructure
This is an important characteristic of semiconductor clusters.
Once fabs reach sufficient scale, suppliers increasingly need production and distribution infrastructure close to the manufacturing site.
⚙️ 2. Axcelis Is Expanding Ion Implantation Equipment Production
Axcelis Technologies represents another part of the supply chain.
The company specializes in ion implantation equipment, one of the key systems used during semiconductor wafer processing.
Ion implantation introduces selected dopant atoms into silicon.
Those dopants modify the electrical characteristics of specific regions of the wafer, helping create transistor structures.
A simplified process looks like:
Silicon Wafer -> Pattern Formation -> Ion Implantation ->
Thermal Processing -> Electrical Properties Modified
As semiconductor production increases, demand also grows for equipment supporting each wafer-processing stage.
Axcelis plans to increase production capabilities in Korea as part of the new investment commitments.
This reinforces another important trend:
Semiconductor equipment suppliers increasingly want manufacturing and service capabilities close to major fabs.
🧱 3. Corning Shows Why Materials Matter Too
Corning plans additional investment in advanced glass and materials used across the display and semiconductor industries.
This broadens the story beyond equipment.
Modern semiconductor manufacturing depends on a large materials ecosystem.
That includes:
- Silicon Wafers
- Photoresists
- Specialty Gases
- Electronic Chemicals
- Advanced Glass
- Ceramics
- Packaging Materials
- Substrates
As devices become more complex, materials performance can become increasingly important.
Advanced packaging provides a good example.
AI processors increasingly combine multiple dies, memory stacks and packaging structures.
That places greater requirements on:
- thermal properties
- dimensional stability
- electrical performance
- precision manufacturing
The semiconductor race therefore increasingly includes a materials race.
🌊 4. Pacifico Energy Connects Semiconductors with Electricity
The most interesting company in the group may appear to be the least semiconductor-related.
Pacifico Energy plans to advance a roughly 3.2 GW offshore wind project in southwestern Korea. The project is expected to contribute power infrastructure supporting a new semiconductor cluster.
This connection is becoming increasingly important.
Semiconductor fabs consume enormous amounts of electricity.
Advanced manufacturing also requires extremely stable power.
That means semiconductor expansion ultimately creates another chain:
AI Demand -> Semiconductor Capacity -> New Fabs ->
Electricity Demand -> Grid & Generation Investment
A semiconductor cluster therefore cannot be planned only around factories.
It also needs sufficient:
Power
Water
Gas
Waste Treatment
Transportation
Industrial Land
The Pacifico Energy investment shows how energy infrastructure is becoming part of semiconductor industrial policy.
⚡ 5. Electricity Is Becoming a Semiconductor Constraint
This issue became even clearer this week.
Reuters reported that Korea Electric Power Corp. had proposed that Samsung Electronics make approximately KRW 20 trillion ($15 billion) in advance electricity payments through 2031 to help fund grid expansion.
A similar proposal of around KRW 5 trillion was reportedly made to SK hynix.
The proposal itself does not mean those payments have been finalized.
But the scale illustrates the underlying problem.
Semiconductor capacity is expanding faster than existing power infrastructure in some regions.
The industrial equation is becoming:
Fab Investment
≠
Fab Capacity Alone
Instead:
Fab
Grid
Generation
Water
Materials
Equipment
=
Real Manufacturing Capacity
This distinction will become increasingly important as Korea builds larger semiconductor clusters.
🧠 6. AI Is Accelerating the Entire Ecosystem
Why is this happening now?
The answer leads back to AI.
Korea’s August semiconductor exports reached a record $46.65 billion, driven by extraordinary global demand for memory chips associated with AI infrastructure.
Samsung Electronics and SK hynix are therefore operating in an environment where memory demand is extremely strong.
But higher semiconductor output cannot happen in isolation.
Every additional wafer processed requires:
Equipment -> Materials -> Chemicals & Gases -> Electricity -> Cooling -> Water
The AI semiconductor boom therefore propagates upstream through the manufacturing supply chain.
This is why investments by companies such as Air Products and Axcelis matter.
They represent the industrial multiplier effect of semiconductor demand.
🏗️ 7. Semiconductor Clusters Are Becoming Industrial Cities
The traditional image of semiconductor investment is a fab.
But a large modern semiconductor cluster is closer to an industrial city.
Around the fabs sit:
Equipment Companies
Lithography
Deposition
Etching
Ion implantation
Inspection
Materials Companies
Wafers
Photoresists
Gases
Chemicals
Packaging materials
Utilities
Electricity
Water
Industrial gases
Waste treatment
Infrastructure
Roads
Logistics
Buildings
Data networks
Human Capital
Engineers
Technicians
Researchers
This creates powerful clustering effects.
Once a region develops enough semiconductor production, suppliers have an incentive to locate nearby.
That can attract additional investment.
The result is a reinforcing cycle:
Fab Investment -> Supplier Investment -> Infrastructure Investment ->
Lower Supply-Chain Friction -> More Fab Investment
🇰🇷 8. Korea Wants More of the Supply Chain at Home
The new investments also fit Korea’s broader industrial strategy.
Global semiconductor supply chains have become increasingly exposed to:
- U.S.-China technology competition
- export controls
- tariffs
- geopolitical risk
- critical-material dependencies
At the same time, the United States and South Korea continue discussions over semiconductor investment and potential U.S. chip-import tariffs.
This increases the strategic value of localized supply chains.
For Korea, attracting foreign semiconductor suppliers means more than attracting capital.
It can also provide:
Supply Security
Technology Access
Local Production
Shorter Logistics
Industrial Resilience
That becomes especially important when semiconductor output is expanding rapidly.
🌎 9. The U.S.–Korea Semiconductor Relationship Is Becoming Two-Way
There is another interesting dimension.
Korean companies are investing heavily in the United States.
Samsung Electronics and SK hynix are expanding U.S. semiconductor manufacturing and packaging operations.
Korean battery manufacturers are also building major U.S. production networks.
Now U.S. suppliers are expanding investments in Korea.
The relationship increasingly looks like:
Korean Investment → United States
and
U.S. Investment → Korea
This suggests semiconductor supply-chain integration is becoming more complex than simple reshoring.
Instead, strategic allies are building interconnected manufacturing ecosystems.
That may become one of the defining characteristics of the semiconductor industry over the next decade.
🔗 10. AI Is Creating an Industrial Investment Multiplier
The most important implication goes beyond the four companies.
Consider how the original demand travels.
AI Models -> AI Servers -> HBM / DRAM -> Semiconductor Fabs -> Equipment ->
Materials & Gases -> Power Infrastructure -> Renewable Energy
One unit of AI demand can therefore trigger investment across multiple industries.
This is what makes the current AI cycle different from a purely digital technology boom.
The economic impact spreads into physical manufacturing.
🧩 Why This Matters
The U.S. Investment in Korea Semiconductor Industry highlights several structural trends.
Semiconductor investment is moving upstream.
Equipment, gases and materials are expanding alongside fabs.
Power is becoming part of semiconductor strategy.
Factories cannot expand without sufficient electricity infrastructure.
Foreign suppliers are localizing.
Proximity to major Korean semiconductor clusters is becoming increasingly valuable.
AI creates demand beyond chips.
Semiconductor growth produces secondary investment across industrial infrastructure.
Supply-chain resilience matters.
Local production can reduce exposure to geopolitical and logistics disruption.
🔭 What to Watch
1. Air Products’ Pyeongtaek Expansion
Watch how gas infrastructure grows alongside Samsung’s semiconductor manufacturing footprint.
2. Axcelis Production
Additional local equipment production would deepen Korea’s semiconductor equipment ecosystem.
3. Corning
Advanced materials could become increasingly important as semiconductor packaging becomes more complex.
4. Pacifico Energy
The 3.2 GW offshore wind project provides an important example of semiconductor and energy infrastructure converging.
5. Korea’s Power Grid
The reported KEPCO proposals to Samsung and SK hynix show that grid investment deserves much more attention.
6. U.S. Semiconductor Tariffs
Future tariff policy could influence where Korean companies allocate new manufacturing investment.
🧭 Atlas Insight
The semiconductor industry’s most important constraint may gradually shift.
For years, the central question was:
Can companies manufacture enough advanced chips?
The question is becoming broader:
Can the industrial ecosystem support enough semiconductor manufacturing?
A fab cannot operate without:
Equipment
Materials
Gases
Water
Electricity
Infrastructure
AI is increasing demand for all of them simultaneously.
That makes the four U.S. investment commitments more important than their $2 billion headline suggests.
The AI semiconductor boom is no longer creating investment only inside fabs. It is pulling capital into the entire industrial system surrounding them.
And that is how technology demand becomes industrial infrastructure demand.
📚 Related Articles
📊 iAtlas Daily #45: Korea Semiconductor Fund Targets the Supply Chain
How Korea is strengthening domestic semiconductor materials, equipment and manufacturing capabilities.
📊 iAtlas Daily #38: AI Data Centers Are Creating a New Industrial Equipment Boom
Why AI demand is spreading from chips into power, cooling and physical infrastructure.
📊 iAtlas Weekly #9 — AI Is Turning Technology Demand into Infrastructure Demand
🔗 References
- Reuters — Four U.S. Companies Commit $2 Billion to Korea
- Yonhap — Seoul Attracts KRW 2.8 Trillion from Four U.S. Firms
- Reuters — KEPCO Power Infrastructure Proposal for Samsung
- Reuters — Korea-U.S. Semiconductor Investment Discussions
About iAtlas
iAtlas is an independent publication covering batteries, semiconductors, OLED, advanced materials, AI, and global industrial trends.
We transform complex industrial developments into clear, reliable, and easy-to-understand insights.
Whether you’re following today’s industry news or building long-term expertise, iAtlas helps you understand not only what happened, but why it matters.
Technology creates change.
Insight creates opportunity.
— iAtlas