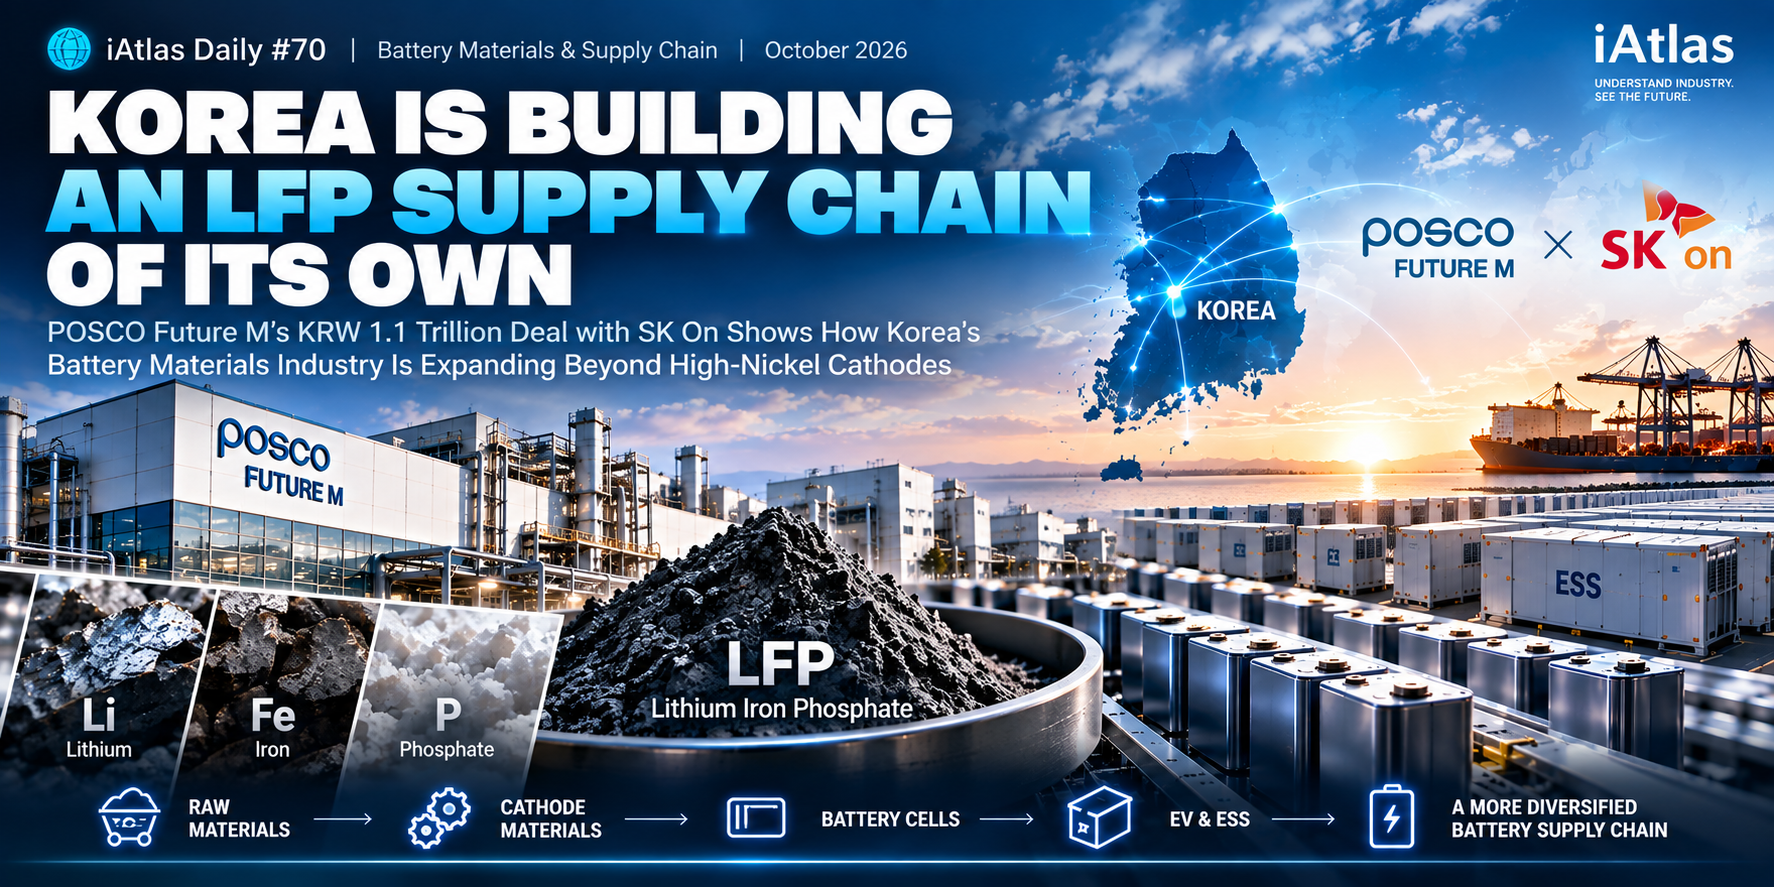
Korea Is Building an LFP Supply Chain of Its Own
POSCO Future M’s KRW 1.1 Trillion Deal with SK On Shows How Korea’s Battery Materials Industry Is Expanding Beyond High-Nickel Cathodes
🔋 iAtlas Daily #70 | Battery Materials & Supply Chain | October 2026
For years, South Korea built one of the world’s strongest battery industries around a particular technological advantage:
High-Nickel Batteries
Korean battery makers became major global suppliers of batteries using cathode chemistries such as:
NCM
Nickel-Cobalt-Manganese
and:
NCA
Nickel-Cobalt-Aluminum
These chemistries offered something extremely valuable to electric vehicles:
High Energy Density
More energy could be stored inside a relatively compact battery.
That helped Korean battery companies become important suppliers to global automakers.
But the battery market is changing.
Energy storage systems are expanding rapidly.
Automakers are introducing more affordable EVs.
Battery customers increasingly care not only about maximum energy density, but also about:
Cost
Cycle Life
Safety
and:
Supply-Chain Stability
And that is pushing another battery chemistry toward the center of Korea’s battery strategy:
LFP
Lithium Iron Phosphate.
In September, POSCO Future M signed a supply agreement worth approximately:
KRW 1.1 Trillion
with SK On for LFP cathode materials.
Supply will run from:
2027 → 2029
with the possibility of extending the contract for another two years.
But the most important part of this story is not the size of the contract.
It is what the contract represents.
South Korea’s battery-material industry is beginning to build a broader chemistry portfolio.
High-Nickel NCM
↓
Mid-Nickel
↓
LMR
↓
LFP
↓
Multi-Chemistry Battery Materials
Korea’s battery strategy is evolving from maximizing battery performance toward serving multiple markets with multiple chemistries.
🌍 The Big Story
For much of the modern EV era, Korean battery companies differentiated themselves through high-performance lithium-ion batteries.
The logic was straightforward.
EV customers wanted:
Longer Driving Range
↓
which required:
Higher Energy Density
↓
which increased demand for:
High-Nickel Cathodes
This created a strong industrial ecosystem around NCM and NCA materials.
Korean companies accumulated expertise across:
Cathode Materials
Cell Manufacturing
Battery Packs
Production Equipment
and:
Automotive Qualification
But another battery ecosystem grew rapidly at the same time.
LFP
And much of that ecosystem developed in China.
1. What Is LFP?
LFP stands for:
Lithium Iron Phosphate
Its cathode chemistry uses:
Lithium
Iron
and:
Phosphate
instead of the nickel and cobalt combinations commonly used in NCM batteries.
That creates a different set of characteristics.
LFP generally offers:
Lower Material Cost
Long Cycle Life
Strong Thermal Stability
and:
Reduced Dependence on Nickel and Cobalt
But there is a trade-off.
Its energy density is generally lower than that of high-nickel batteries.
That means LFP was historically less attractive for applications where maximum driving range was the overriding priority.
But battery markets no longer optimize for only one variable.
2. Battery Competition Is No Longer Just About Range
During the early EV market, one question dominated:
How far can the vehicle travel?
Range anxiety was one of the biggest barriers to EV adoption.
That made energy density extremely valuable.
But the market is becoming more segmented.
Some customers still want:
Premium EVs
with maximum range.
Others want:
Affordable EVs
And energy-storage systems have completely different requirements.
For ESS, priorities can include:
Cost
Cycle Life
Safety
Reliability
and:
Total Lifetime Economics
That changes the chemistry equation.
3. ESS Is Giving LFP Another Growth Engine
An EV battery needs to move.
Weight matters.
Volume matters.
Every kilogram affects vehicle efficiency.
A stationary battery does not face the same constraint.
An ESS installation can occupy:
A Container
A Building
or:
A Dedicated Site
That means slightly lower energy density can be acceptable if the battery provides:
Lower Cost
Long Life
and:
Strong Safety Characteristics
This makes LFP particularly attractive for stationary energy storage.
And ESS demand is becoming increasingly important to the global battery industry.
4. The Battery Market Is Splitting into Different Jobs
The future battery market may increasingly resemble this:
Premium EV
Priority:
Energy Density + Range
Potential chemistry:
High-Nickel NCM / NCA
Mainstream EV
Priority:
Balanced Performance + Cost
Potential chemistry:
Mid-Nickel / LFP / Other Alternatives
Entry-Level EV
Priority:
Affordability
Potential chemistry:
LFP
Energy Storage
Priority:
Cost + Cycle Life + Safety
Potential chemistry:
LFP
and potentially:
Sodium-Ion
This is important.
The battery industry may not converge toward one universal chemistry.
It may become:
Multi-Chemistry
5. That Changes the Strategy for Materials Companies
A cathode-material company serving only one chemistry is effectively exposed to one part of the battery market.
But if customers increasingly use different chemistries for different applications, materials suppliers need broader portfolios.
POSCO Future M’s traditional strength has been centered on ternary cathode materials such as:
NCM
and:
NCA
The company’s current battery-material portfolio also includes development across:
Ultra-High-Nickel
High-Voltage Mid-Nickel
LMR
LMFP
and:
LFP
This is a significant strategic shift.
The company is no longer preparing for one battery market.
It is preparing for:
Several Battery Markets at Once
POSCO Future M’s published materials portfolio now explicitly positions LFP for entry-level EV and ESS applications while retaining high-nickel products for premium applications.
6. The SK On Contract Makes the Shift Commercial
Technology development is one thing.
Commercial contracts are another.
On September 22, POSCO Future M signed a large-scale LFP cathode-material supply contract with SK On.
The contract is worth approximately:
KRW 1.1 Trillion
and covers:
2027
↓
2028
↓
2029
The contract can also be extended by:
Two Additional Years
if both companies agree.
This is not simply an R&D partnership.
It represents commercial demand for Korean-produced LFP cathode material.
7. And This Is Not POSCO Future M’s Only LFP Deal
The SK On contract follows another major development.
In August, POSCO Future M announced an agreement with another Korean battery maker to supply:
More Than 190,000 Tonnes
of LFP cathode materials.
That supply is planned across:
2027 → 2032
The company said the agreement was intended primarily to respond to rapidly growing:
North American ESS Demand
This means the SK On contract is not an isolated transaction.
It is part of a broader commercialization push.
8. Korea Is Trying to Close a Strategic Gap
China built an enormous advantage in LFP.
That advantage extends beyond cell manufacturing.
It includes:
Raw Materials
↓
Cathode Materials
↓
Battery Cells
↓
Manufacturing Equipment
↓
ESS Systems
This creates a deeply integrated industrial ecosystem.
Korean companies historically concentrated more heavily on high-energy-density ternary batteries.
That strategy worked extremely well for premium EV markets.
But as LFP demand expands, depending heavily on external LFP supply chains becomes strategically uncomfortable.
Korean manufacturers therefore have an incentive to develop:
A Domestic LFP Ecosystem
9. But “Korean LFP” Does Not Mean Everything Comes from Korea
This distinction matters.
Battery supply chains are global.
A cathode material manufactured in Korea may still depend on:
Lithium
Precursors
Processing Technology
or:
Intermediate Materials
from other countries.
POSCO Future M itself is working with CNGR and FINO through CNP New Material Technology to build its dedicated LFP production capability in Pohang.
So the emerging model is not:
Complete Self-Sufficiency
It is closer to:
Strategic Localization
The objective is to place more critical manufacturing capability inside Korea while diversifying the broader supply chain.
10. POSCO Future M Is Building Dedicated LFP Capacity
The company has already moved beyond planning.
POSCO Future M approved a dedicated LFP cathode-material plant at:
Pohang
The facility is being developed through CNP New Material Technology.
The planned capacity can expand to:
50,000 Tonnes per Year
with mass production targeted for 2027.
The output is intended for ESS applications.
This is important because it creates a dedicated industrial base rather than relying only on laboratory or pilot production.
11. But Dedicated Factories Take Time
There is an obvious problem.
Customers need material now.
Building a completely new factory can take years.
POSCO Future M therefore adopted another strategy:
Convert Existing Production Lines
The company has converted part of its existing high-nickel cathode-material lines at its Pohang plant to LFP production.
Mass-production supply is scheduled to begin:
By the End of 2026
This is a good example of manufacturing flexibility.
12. Existing Assets Can Become Strategic
This strategy reveals something important about industrial manufacturing.
A factory is not always permanently tied to one product.
Existing:
Buildings
Utilities
Material Handling
Quality Systems
Engineering Teams
and:
Production Infrastructure
can sometimes be adapted to new products.
That can shorten the time required to enter a growing market.
The strategic sequence becomes:
Existing NCM Capacity
↓
Partial Line Conversion
↓
Early LFP Supply
↓
Dedicated LFP Factory
↓
Expanded LFP Capacity
Instead of waiting for an entirely new facility to be completed.
13. This Is Manufacturing Optionality
We discussed a similar concept in the battery-cell industry.
A flexible battery factory may shift production between:
EV
and:
ESS
depending on demand.
The same logic can apply upstream.
A materials company able to adapt production infrastructure across different cathode chemistries gains:
Manufacturing Optionality
That can become valuable when market demand changes faster than factories can be built.
14. LFP Is Not Replacing High-Nickel
This is one of the most important distinctions.
The story should not be interpreted as:
Korea is abandoning high-nickel batteries.
That is not what is happening.
High-nickel cathodes remain important for applications where:
Energy Density
Driving Range
and:
Weight
are critical.
POSCO Future M continues developing premium cathode materials, including ultra-high-nickel products.
The strategy is therefore:
High-Nickel
+
Mid-Nickel
+
LMR
+
LFP
rather than:
High-Nickel → LFP
15. The Battery Market Is Becoming a Portfolio Business
This resembles other mature industries.
Automakers do not manufacture one vehicle for every customer.
Semiconductor companies do not use one chip architecture for every workload.
Likewise, battery companies may increasingly offer different chemistry platforms for different applications.
The competitive question becomes:
Can you provide the right battery for the right market?
That is different from:
Which battery chemistry is best?
There may be no universal answer.
16. LMR Adds Another Option
POSCO Future M is also developing:
LMR
Lithium-Manganese-Rich cathode materials.
LMR attempts to reduce dependence on expensive metals such as nickel and cobalt while increasing manganese content.
POSCO Future M says its LMR approach could provide energy density up to around 30% higher than LFP while targeting competitive economics when recycling is considered.
This creates another potential layer between:
Premium High-Nickel
and:
Low-Cost LFP
17. LMFP Could Fill Another Gap
Another chemistry in the company’s portfolio is:
LMFP
Lithium Manganese Iron Phosphate.
LMFP builds on LFP chemistry by adding manganese.
The objective is to retain much of LFP’s cost advantage while improving energy density.
POSCO Future M describes LMFP as targeting roughly:
15–20% higher energy density
than conventional LFP while maintaining a similar price level.
Again, the pattern is clear.
The market is not moving toward fewer chemistries.
It may be moving toward:
More Specialized Chemistries
18. Sodium-Ion Makes the Portfolio Even Wider
Last week’s iAtlas Daily examined another chemistry:
Sodium-Ion
Sodium-ion introduces a fundamentally different materials system.
Its potential strengths include:
Resource Availability
Cost Potential
and:
Low-Temperature Performance
depending on cell design.
If sodium-ion reaches large-scale commercialization, the battery market could eventually include:
High-Nickel
Mid-Nickel
LMR
LFP
LMFP
Sodium-Ion
and other emerging systems.
Battery manufacturing is becoming more diversified, not less.
19. That Creates a New Challenge for Suppliers
More chemistries mean more complexity.
Materials companies need different:
Raw Materials
Process Conditions
Quality Specifications
and:
Customer Qualifications
Battery manufacturers may need different:
Electrode Recipes
Formation Conditions
Process Windows
and:
Equipment Settings
The benefit is flexibility.
The cost is complexity.
Managing that complexity may become another competitive capability.
20. Raw Materials Still Determine Competitiveness
LFP removes two materials that attract significant strategic attention:
Nickel
and:
Cobalt
But LFP still requires:
Lithium
That means supply-chain strategy remains important.
POSCO Future M says it plans to improve LFP cost competitiveness by eventually applying a process using lithium sourced from POSCO Group’s:
Argentine Salt Lakes
This is particularly interesting.
It connects:
Lithium Resource
↓
Cathode Material
↓
Battery Manufacturer
into a broader group-level supply chain.
21. This Connects Directly to Last Week’s Nickel Story
Last week’s Daily #68 examined how battery competition is moving upstream into:
Nickel
The LFP story provides an interesting counterpoint.
Instead of securing more nickel, LFP reduces dependence on nickel entirely.
These are two different responses to the same strategic problem:
Material Risk
One strategy is:
Secure the Material
Another is:
Change the Chemistry
Both can improve supply-chain resilience.
22. Chemistry Is Therefore a Supply-Chain Decision
Battery chemistry is often discussed primarily in technical terms.
Energy density.
Cycle life.
Voltage.
Safety.
But chemistry also determines:
Which Minerals Are Needed
Where They Come From
How They Are Processed
and:
Which Countries Control the Supply Chain
That means choosing a battery chemistry is partly:
A Geopolitical Decision
and:
A Supply-Chain Decision
not just an electrochemical one.
23. North America Makes This More Important
The United States is trying to build more battery manufacturing capacity domestically.
But manufacturing batteries inside North America does not automatically create a localized battery supply chain.
The materials also matter.
This is particularly important for:
Cathode Materials
Anode Materials
Lithium
Graphite
and:
Electrolytes
Korean battery companies therefore occupy an interesting position.
They can potentially connect:
Korean Materials
↓
North American Battery Factories
↓
U.S. EV / ESS Markets
24. ESS Could Become a Major Entry Point
The rapid expansion of energy storage gives Korean LFP suppliers an important market opportunity.
Unlike premium EVs, ESS does not require the highest possible gravimetric energy density.
Instead, economics often emphasize:
Cost per Cycle
Safety
Lifetime
and:
Reliability
Those characteristics align well with LFP.
This is why POSCO Future M explicitly identifies rapidly growing ESS demand as one of the primary drivers behind its LFP expansion.
25. AI Data Centers Are Adding Another Demand Layer
Data centers are consuming increasing amounts of electricity.
That creates demand not only for:
Generation
but also:
Grid Stability
Backup Power
and:
Energy Storage
POSCO Future M specifically cited rising power demand associated with AI data-center expansion as one factor supporting ESS demand.
This creates an interesting industrial chain:
AI Compute
↓
Data Centers
↓
Electricity Demand
↓
Energy Storage
↓
LFP Batteries
↓
LFP Cathode Materials
A digital technology trend eventually becomes a materials demand story.
26. But Cost Competition Will Be Difficult
Building Korean LFP capacity does not automatically make Korean LFP globally competitive.
China already has:
Large Production Scale
Mature Supply Chains
Experienced Manufacturers
and:
Strong Cost Competitiveness
Korean suppliers therefore need to solve a difficult equation:
Localization
Quality
Supply-Chain Compliance
Competitive Cost
This may be the biggest challenge.
27. Scale Will Matter
Cathode-material manufacturing benefits from scale.
Large production volumes can improve:
Fixed-Cost Absorption
Procurement
Process Learning
and:
Equipment Utilization
This is why long-term supply contracts matter.
They provide greater visibility into future demand.
That can justify:
Capital Investment
The SK On agreement therefore does more than generate revenue.
It helps create the commercial foundation for expanding LFP manufacturing.
28. The Contract Also Deepens the SK On Relationship
POSCO Future M already supplied:
Anode Materials
to SK On.
The new agreement adds:
Cathode Materials
According to POSCO Future M, the contract also means the company now supplies cathode and anode materials across all three major Korean battery manufacturers.
That broadens its position from a chemistry supplier toward a more diversified battery-material platform.
29. Korea’s Battery Advantage Is Becoming Broader
Korea’s battery industry originally built strong competitive positions around:
High-Nickel Cathodes
Advanced Cell Manufacturing
Global Automotive Customers
and:
Manufacturing Equipment
The next stage may add:
LFP
LMR
LMFP
Silicon Anodes
Synthetic Graphite
and other materials.
The industrial strategy becomes:
Portfolio Expansion
rather than reliance on one technological advantage.
30. This Is a Sign of a Maturing Battery Industry
Early industries often search for:
The Winning Technology
Mature industries increasingly develop:
The Right Technology for Each Application
Battery markets appear to be moving in that direction.
The question is becoming less:
NCM or LFP?
and more:
Which chemistry makes the most sense for this specific product, market and supply chain?
That is a much more sophisticated industrial question.
🧩 Why This Matters
Korea is expanding beyond its traditional high-nickel strength.
POSCO Future M’s LFP contracts show that Korean materials companies are building broader cathode portfolios.
LFP is becoming commercially important for both ESS and lower-cost EVs.
The chemistry’s cost, cycle-life and safety characteristics make it suitable for markets where maximum energy density is not the only priority.
Existing manufacturing infrastructure can accelerate market entry.
POSCO Future M is converting part of its Pohang high-nickel lines to LFP production before dedicated capacity reaches full operation.
The battery industry is becoming multi-chemistry.
High-nickel, mid-nickel, LFP, LMR, LMFP and sodium-ion can serve different market requirements.
Chemistry is also supply-chain strategy.
Different battery chemistries create different dependencies on lithium, nickel, cobalt, manganese, iron and other materials.
The biggest challenge may be cost.
Korean LFP producers must compete against a highly developed Chinese LFP ecosystem while building localized and diversified supply chains.
🔭 What to Watch
LFP Mass Production
POSCO Future M plans to begin LFP mass-production supply from converted Pohang lines by the end of 2026. The next milestone is whether the ramp proceeds on schedule.
Dedicated Pohang Capacity
Watch the development of the dedicated LFP facility and its planned expansion toward 50,000 tonnes per year.
SK On
The 2027 start of the SK On supply contract will show how Korean-made LFP materials enter the company’s battery portfolio.
North American ESS
Continued ESS growth could become one of the strongest demand drivers for Korean LFP materials.
Cost Competitiveness
The key question is whether Korean LFP can narrow the cost gap with established Chinese supply chains.
Chemistry Diversification
Watch LMR and LMFP alongside LFP. Korea’s strategy may ultimately be broader than simply adding one new cathode chemistry.
🧭 Atlas Insight
For years, Korea’s battery advantage could be summarized relatively simply:
High Performance
High-nickel cathodes.
Long-range EV batteries.
Premium automotive customers.
That strategy helped Korean companies build a major position in the global battery industry.
But the battery market is changing.
The next decade may not be dominated by one chemistry.
Instead:
Premium EVs
may prioritize energy density.
Entry-Level EVs
may prioritize affordability.
ESS
may prioritize lifetime economics.
Cold-Climate Applications
may value different performance characteristics.
That creates room for multiple battery systems.
And when the market becomes multi-chemistry, suppliers need to become multi-chemistry too.
POSCO Future M’s LFP expansion therefore matters for more than one KRW 1.1 trillion contract.
It represents a broader strategic transition:
From
How can Korea make higher-performance batteries?
Toward
How can Korea supply the right battery materials for every major battery market?
That is a different industrial strategy.
And potentially a more resilient one.
The next phase of Korea’s battery industry may not be defined by choosing between high-nickel and LFP. It may be defined by mastering both.
📚 Related Articles
📰 iAtlas Daily #67: Sodium-Ion Batteries Are Moving from the Lab to the Factory
Sodium-ion shows why battery markets are moving toward multiple chemistry platforms rather than one universal battery technology.
📰 iAtlas Daily #68: The Battery Supply Chain Is Moving Upstream into Nickel
Nickel provides the opposite side of the materials strategy: instead of removing a critical material through chemistry, companies can move upstream to secure it.
📰 iAtlas Daily #65: LG Energy Solution Is Building an ESS Manufacturing Network Across North America
The growth of North American ESS manufacturing helps explain why LFP materials are becoming increasingly important to Korean battery companies.
🔗 References
- POSCO Future M — LFP Cathode Material Supply Contract with SK On
- POSCO Future M — LFP Cathode Material Plant for ESS
- POSCO Future M — LFP Joint Venture with CNGR and FINO
- POSCO Future M — Battery Materials Portfolio
- POSCO Future M — 190,000-Tonne LFP Supply Agreement
ℹ️ About iAtlas
iAtlas is an independent publication covering batteries, semiconductors, OLED, advanced materials, AI, and global industrial trends.
We transform complex industrial developments into clear, reliable, and easy-to-understand insights.
Whether you’re following today’s industry news or building long-term expertise, iAtlas helps you understand not only what happened, but why it matters.
Technology creates change.
Insight creates opportunity.
— iAtlas