China’s CXMT Is Moving Beyond DRAM into NAND Flash
As Its Fifth-Generation DRAM Platform Enters Mass Production, China’s Memory Champion Is Exploring a Second Major Memory Market
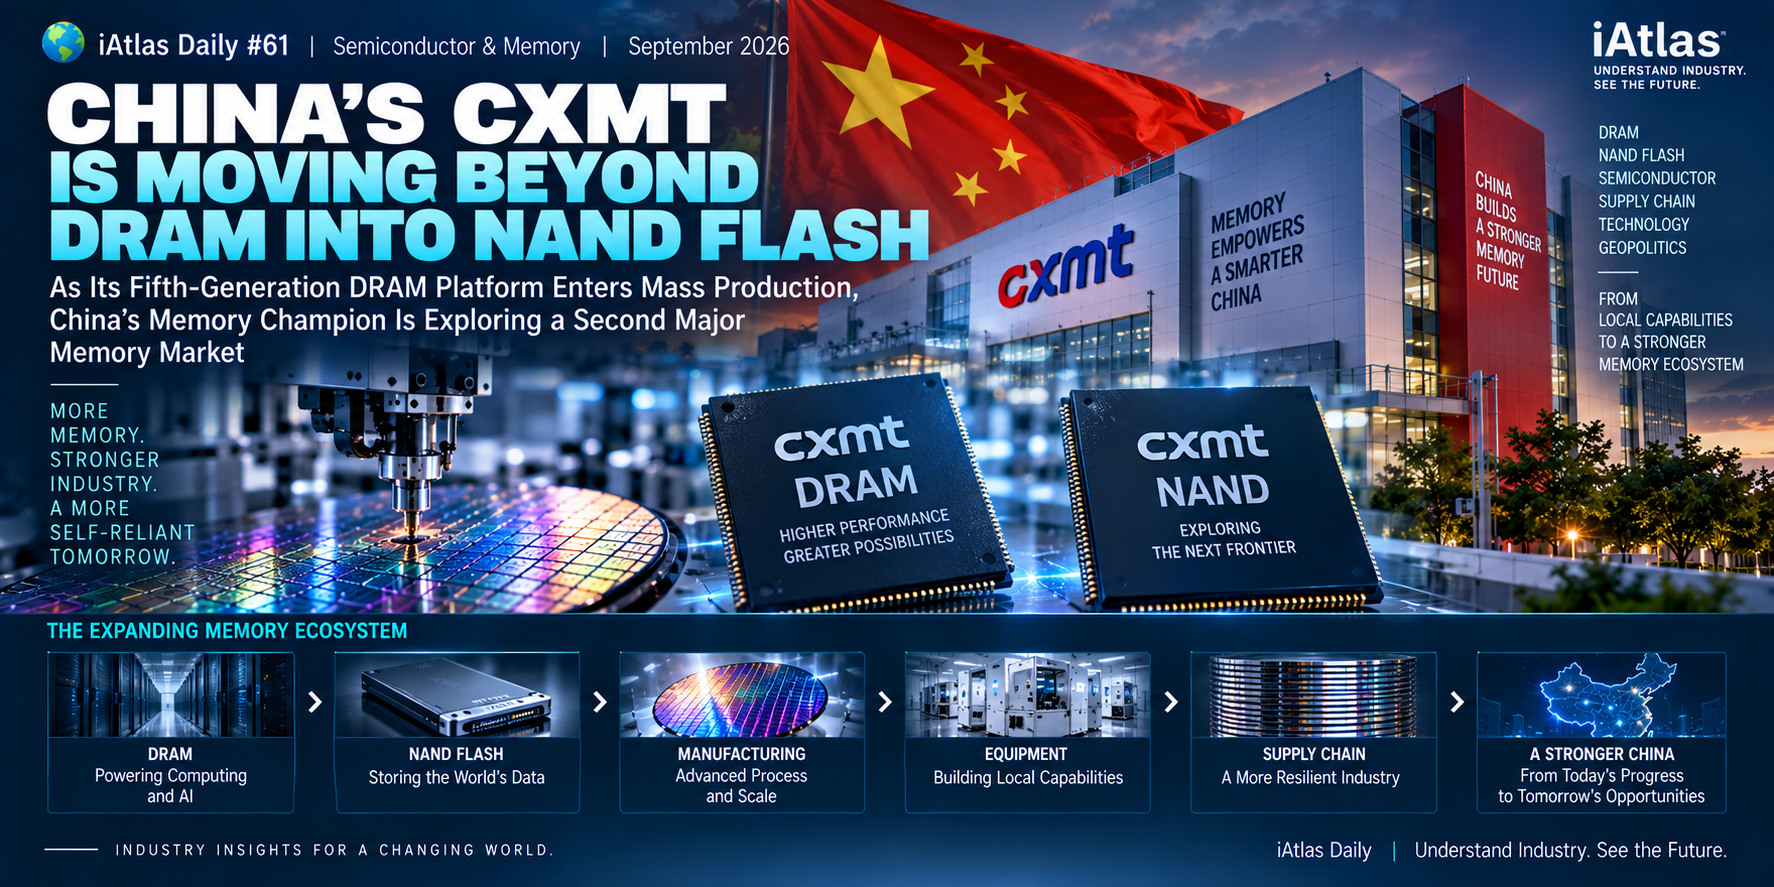
💾 iAtlas Daily #61 | Semiconductor & Memory | September 2026
China’s memory-chip industry is entering a new phase.
For years, the country’s two leading memory manufacturers occupied relatively distinct positions.
CXMT
→ DRAM
YMTC
→ NAND Flash
That division is beginning to blur.
ChangXin Memory Technologies, better known as CXMT, is preparing an R&D production line for NAND flash memory at a new facility in Beijing.
At the same time, CXMT announced on September 20 that its fifth-generation DRAM technology platform has entered mass production.
Together, the developments point toward a broader strategic shift:
DRAM
↓
Technology Advancement
↓
NAND R&D
↓
Broader Memory Portfolio
↓
China’s Expanding Memory Ecosystem
But there is an important distinction.
CXMT is not yet commercially producing NAND at scale.
Its NAND initiative remains an R&D effort, and it is still unclear whether or when the project will progress to large-scale commercial manufacturing.
The significance of CXMT’s NAND plan is not what it produces today. It is what China wants its memory industry to become tomorrow.
🌏 The Big Story
CXMT is China’s leading domestic DRAM manufacturer.
DRAM provides the temporary working memory used by processors.
NAND serves a different function.
It stores data persistently in products such as:
Smartphones
PCs
SSDs
Enterprise Storage
Data Centers
Until now, China’s domestic memory industry has largely been divided between two companies.
| Company | Traditional Focus |
|---|---|
| CXMT | DRAM |
| YMTC | NAND Flash |
Now that boundary is weakening.
Reuters reported that CXMT plans to establish a NAND flash R&D production line at a new Beijing facility and has established a research institute in Beijing whose projects include NAND development.
CXMT has also discussed the plans with prospective customers, including a startup interested in NAND chips for storage products used in AI systems and supercomputers.
If CXMT eventually moves from research into commercial NAND production, China’s memory landscape could change significantly.
🧠 1. First, What Is the Difference Between DRAM and NAND?
Both are memory semiconductors.
But they perform fundamentally different jobs.
DRAM
DRAM is working memory.
It temporarily stores information that a processor needs immediately.
Think of it as:
The desk where you are currently working.
More desk space allows more information to remain readily accessible.
DRAM is therefore critical in:
Servers
PCs
Smartphones
AI Systems
NAND Flash
NAND is storage memory.
It keeps information even after power is removed.
Think of it as:
The filing cabinet where information is stored.
NAND is used in:
SSDs
Smartphones
Memory Cards
Enterprise Storage
Data Centers
The basic distinction is:
DRAM
→ Work with data
NAND
→ Store data
Modern computing systems need both.
💾 2. The Global Memory Industry Has Two Major Markets
The semiconductor industry is often discussed as if memory were a single market.
In reality, DRAM and NAND have different technologies and competitive structures.
DRAM
Major players include:
Samsung Electronics
SK hynix
Micron
and increasingly:
CXMT
NAND
Major players include:
Samsung Electronics
SK hynix
Micron
Kioxia
SanDisk
and:
YMTC
This makes Samsung and SK hynix particularly interesting.
They compete across both major memory categories.
CXMT historically did not.
Its NAND project suggests that could eventually change.
🇨🇳 3. China Built Two Memory Champions
China’s domestic memory strategy produced two major companies.
CXMT
Focused primarily on:
DRAM
YMTC
Focused primarily on:
NAND
This effectively created two specialized national champions.
The structure looked like:
China Memory Industry
↙️ ↘️
CXMT YMTC
DRAM NAND
But specialization has limits.
As memory becomes more strategically important, both companies have incentives to broaden their technology portfolios.
🔄 4. Now the Two Companies Are Moving into Each Other’s Markets
CXMT’s NAND initiative is particularly interesting because movement is occurring in both directions.
Reuters previously reported that YMTC had provided samples of low-power DRAM to customers as it evaluated entering that market.
Now CXMT is exploring NAND.
The structure could eventually become:
CXMT
DRAM → NAND
YMTC
NAND → DRAM
The two Chinese memory champions that historically occupied separate markets could increasingly become direct competitors.
That could have implications not only inside China.
It could eventually affect the global memory market.
🏭 5. CXMT Is Strengthening Its Core DRAM Business at the Same Time
CXMT’s NAND plan does not mean it is abandoning DRAM.
Quite the opposite.
On September 20, the company announced that its fifth-generation memory technology platform has entered mass production.
According to CXMT, the platform improves:
Performance
Power Consumption
Manufacturing Cost
and:
Wafer Productivity
The company says the new process increases gross die output per wafer by at least 50% compared with its previous generation.
This matters because CXMT’s strategy appears to be:
Strengthen DRAM
Explore NAND
rather than simply switching markets.
📱 6. CXMT Is Also Advancing LPDDR5X
CXMT introduced two new 24-gigabit LPDDR5X products based on its fifth-generation platform.
LPDDR is particularly important for:
Smartphones
Tablets
Portable Electronics
and increasingly:
Edge Computing Devices
The new chips provide 50% more storage capacity than CXMT’s previous generation, according to the company.
This demonstrates how rapidly China’s DRAM capabilities are evolving.
CXMT is no longer relevant simply because it is a domestic Chinese supplier.
Its technology progression increasingly makes it a company global memory manufacturers need to watch.
📊 7. CXMT Is Already Becoming Significant in DRAM
The market numbers illustrate the change.
According to TrendForce data cited in recent reporting, CXMT reached approximately 9.5% of global DRAM revenue in Q2 2026.
The market remained led by:
Samsung — 39.4%
SK hynix — 24.9%
Micron — 23.3%
with:
CXMT — 9.5%.
CXMT remains smaller than the three established global leaders.
But a near-10% share is no longer insignificant.
China has developed a meaningful fourth DRAM competitor.
🏗️ 8. NAND Is Technologically Different
This is where expectations need to be realistic.
CXMT cannot simply take its DRAM process and start manufacturing competitive NAND.
The technologies are fundamentally different.
Modern NAND increasingly relies on:
3D NAND
Instead of shrinking memory cells only horizontally, manufacturers stack memory layers vertically.
Conceptually:
Traditional NAND
→ 2D scaling
versus:
Modern NAND
→ Layer
→ Layer
→ Layer
→ Layer
→ Layer
→ Hundreds of Layers
Manufacturing these structures requires different:
Etch
Deposition
Integration
Bonding
Yield Management
and process expertise.
CXMT therefore faces a significant learning curve.
🔬 9. An R&D Line Is Not a Mass-Production Fab
This distinction is essential.
The current plan is for an:
R&D Production Line
That means CXMT can develop and test processes.
It does not mean commercial NAND chips are about to enter the market.
Reuters reports that it remains unclear:
- when the R&D line will begin operating;
- whether CXMT will move into large-scale commercial NAND manufacturing.
The realistic progression would be:
Research
↓
Process Development
↓
Experimental Production
↓
Yield Improvement
↓
Customer Qualification
↓
Commercial Production
↓
Mass Production
CXMT is near the beginning of that path.
💰 10. But CXMT Has Capital to Invest
Memory manufacturing is extraordinarily capital intensive.
Developing a second major memory technology requires:
Facilities
Equipment
Engineers
Materials
Process Development
and years of investment.
CXMT has significantly strengthened its financial position.
The company raised approximately $8.6 billion through its 2026 IPO, according to Reuters.
It is also expanding its manufacturing footprint in Beijing.
That gives CXMT financial capacity to pursue technology beyond its existing DRAM business.
📈 11. Why Enter NAND Now?
Timing matters.
The global memory market is currently experiencing tight supply.
AI infrastructure has dramatically increased demand not only for compute processors and HBM but also for conventional memory and storage.
AI servers require:
GPU / Accelerator
↓
HBM
Server DRAM
Enterprise SSD
↓
NAND Flash
AI therefore creates demand across several memory layers.
The storage side of the AI infrastructure story has become increasingly important.
🗄️ 12. AI Servers Need Enormous Storage
AI models require vast amounts of data.
That data must be stored somewhere.
Enterprise AI infrastructure therefore depends heavily on:
SSDs
And SSDs depend on:
NAND Flash
The chain is:
AI Model
↓
Training Data
↓
Storage
↓
Enterprise SSD
↓
NAND Flash
This is one reason NAND has become strategically relevant during the AI infrastructure expansion.
CXMT has reportedly discussed its NAND plans with a startup interested in storage products for AI systems and supercomputers.
⚠️ 13. Memory Supply Is Already Tight
The broader memory market is experiencing significant supply pressure.
Smaller smartphone and laptop manufacturers are preparing for shortages extending through at least 2027, while some industry projections suggest capacity constraints could persist even longer.
This matters for CXMT.
New entrants normally face enormous competitive pressure when established suppliers have excess capacity.
A shortage creates a different environment.
Customers become more willing to:
Qualify Alternative Suppliers
Accept New Products
Diversify Procurement
This could create an opening for Chinese memory suppliers.
🇰🇷 14. What Does This Mean for Samsung and SK hynix?
For Korean memory manufacturers, the immediate impact should not be overstated.
CXMT does not yet have commercial NAND production.
Samsung and SK hynix possess:
Decades of NAND Experience
Large-Scale Manufacturing
Advanced Process Technology
Enterprise SSD Products
Global Customers
High Manufacturing Yields
CXMT cannot replicate those capabilities quickly.
But strategically, the direction matters.
Samsung and SK hynix already compete with CXMT in DRAM.
If CXMT eventually succeeds in NAND, competition could expand across:
DRAM
NAND
and eventually potentially:
Enterprise Storage
The competitive overlap would become much broader.
🇨🇳 15. YMTC May Face the More Immediate Strategic Challenge
Interestingly, the company most directly affected may initially be another Chinese company.
YMTC
YMTC is China’s established NAND manufacturer.
CXMT entering NAND therefore creates domestic competition.
Historically:
CXMT → Chinese DRAM Leader
YMTC → Chinese NAND Leader
Future:
CXMT → DRAM + NAND?
YMTC → NAND + DRAM?
The two companies could increasingly compete for:
Customers
Engineers
Equipment
Capital
Government Support
and:
Market Share
China’s memory industry could become internally competitive as well as globally competitive.
🧩 16. China Is Building Redundancy into Its Memory Industry
There is another way to interpret the strategy.
Instead of relying on:
One Domestic DRAM Supplier
and:
One Domestic NAND Supplier
China could eventually have multiple companies capable of producing both technologies.
That creates:
Redundancy
From an industrial-policy perspective, redundancy can improve resilience.
If one company faces:
Technology Problems
Capacity Constraints
Export Restrictions
or:
Supply Disruptions
another domestic supplier may provide an alternative.
This is particularly important for semiconductors, where China continues to pursue greater technological self-reliance.
⚙️ 17. Equipment Becomes a Critical Constraint
There is a major obstacle.
Advanced memory manufacturing requires sophisticated semiconductor equipment.
This includes:
Lithography
Etch
Deposition
Metrology
Cleaning
Process Control
Export restrictions can limit Chinese manufacturers’ access to some advanced foreign semiconductor technologies.
That means CXMT’s success increasingly depends on another layer:
China’s Domestic Semiconductor Equipment Industry
The chain becomes:
Memory Chip
↓
Fab
↓
Equipment
↓
Components
↓
Materials
This brings us back to one of the central themes iAtlas has been following.
Semiconductor competition continues moving deeper into the supply chain.
🏭 18. Domestic Equipment Development Could Become More Important
Today’s CXMT announcement also provides an interesting clue.
Reuters reports that the company’s fifth-generation DRAM platform was developed partly through simulations and collaboration with Chinese equipment manufacturers.
That is strategically significant.
China’s semiconductor localization is therefore not occurring only at the chip level.
It increasingly involves:
Chipmakers
Equipment Companies
Materials Suppliers
Research Institutions
This is how a semiconductor ecosystem deepens.
🌐 19. Memory Competition Is Becoming More Geopolitical
Memory was once largely an industry competition between companies.
Increasingly, it is also competition between industrial ecosystems.
South Korea
Samsung Electronics
SK hynix
United States
Micron
Japan
Kioxia
China
CXMT
YMTC
At the same time, countries are increasingly concerned about where memory is physically manufactured.
SK hynix’s Solidigm is reportedly considering a NAND manufacturing facility in the United States, with upstate New York among the potential locations. No final investment decision has been made.
Memory is therefore becoming both:
Technology Competition
and:
Geographic Competition
🗺️ 20. The Global Memory Map Could Become More Complex
For years, global memory was extraordinarily concentrated.
That remains true.
But several developments are occurring simultaneously:
CXMT expanding DRAM
CXMT exploring NAND
YMTC exploring DRAM
Solidigm considering U.S. NAND manufacturing
AI driving new memory demand
This creates a more complex industry map.
The future may not simply be:
Samsung vs. SK hynix vs. Micron
Instead, competition could increasingly involve:
Established Global Leaders
Chinese Memory Champions
Regional Manufacturing Strategies
The memory industry is becoming both broader and more geographically distributed.
🧩 Why This Matters
CXMT’s NAND plan highlights several important changes.
China’s memory industry is broadening.
CXMT is exploring expansion beyond its traditional DRAM specialization.
DRAM and NAND boundaries are beginning to blur.
CXMT and YMTC are moving toward each other’s markets.
CXMT’s core DRAM technology continues to advance.
Its fifth-generation platform has now entered mass production.
NAND should not yet be treated as commercial production.
The current project is an R&D production line with no confirmed mass-production timetable.
Memory competition is becoming geopolitical.
China, Korea and the U.S. increasingly view memory manufacturing as strategic industrial capacity.
🔭 What to Watch
CXMT NAND R&D Line
The first question is when the Beijing line actually becomes operational.
Technology
Watch for information about:
Layer Count
Architecture
Process Technology
and:
Yield
Commercial Production
The most important milestone will be whether CXMT commits to high-volume NAND manufacturing.
Customer Qualification
Watch whether Chinese SSD and data-center companies begin testing CXMT NAND.
YMTC DRAM
YMTC’s movement toward low-power DRAM could create competition in the opposite direction.
Samsung & SK hynix
Watch whether Chinese competition begins influencing pricing or investment strategies in conventional DRAM and NAND.
Chinese Equipment
CXMT’s collaboration with domestic equipment manufacturers deserves particular attention as China’s semiconductor ecosystem develops.
🧭 iAtlas Insight
CXMT’s NAND plan is easy to exaggerate.
It does not mean China suddenly has another competitive NAND manufacturer.
The company still needs to move through:
Research
↓
Process Development
↓
Trial Production
↓
Yield Improvement
↓
Qualification
↓
Mass Production
That could take years.
But the direction is strategically important.
China’s memory industry used to have a relatively simple structure:
CXMT = DRAM
YMTC = NAND
That structure is beginning to disappear.
The future could look more like:
CXMT
DRAM + NAND
↕
YMTC
NAND + DRAM
surrounded by an increasingly capable domestic semiconductor equipment and materials ecosystem.
And that changes the bigger question.
It is no longer simply:
Can China build competitive DRAM or NAND?
It is becoming:
Can China build a complete memory industry?
For Samsung, SK hynix and Micron, that is the development worth watching.
📚 Related Articles
📰 iAtlas Daily #59: India Is Building More Than Semiconductor Fabs
📰 iAtlas Weekly #11: Industrial Competition Is Moving Deeper into the Supply Chain
🔗 References
Reuters — CXMT Eyes NAND Flash Push
Reuters — CXMT Fifth-Generation DRAM Platform Enters Mass Production
TrendForce — CXMT NAND R&D Line and Memory Market Shares
ℹ️ About iAtlas
iAtlas is an independent publication covering batteries, semiconductors, OLED, advanced materials, AI, and global industrial trends.
We transform complex industrial developments into clear, reliable, and easy-to-understand insights.
Whether you’re following today’s industry news or building long-term expertise, iAtlas helps you understand not only what happened, but why it matters.
Technology creates change.
Insight creates opportunity.
— iAtlas