AI Infrastructure Supply Chain Is Reshaping Industry
From AI Memory and Advanced Packaging to Critical Battery Materials
📊 iAtlas Weekly #8 | Weekly Briefing | August 2026
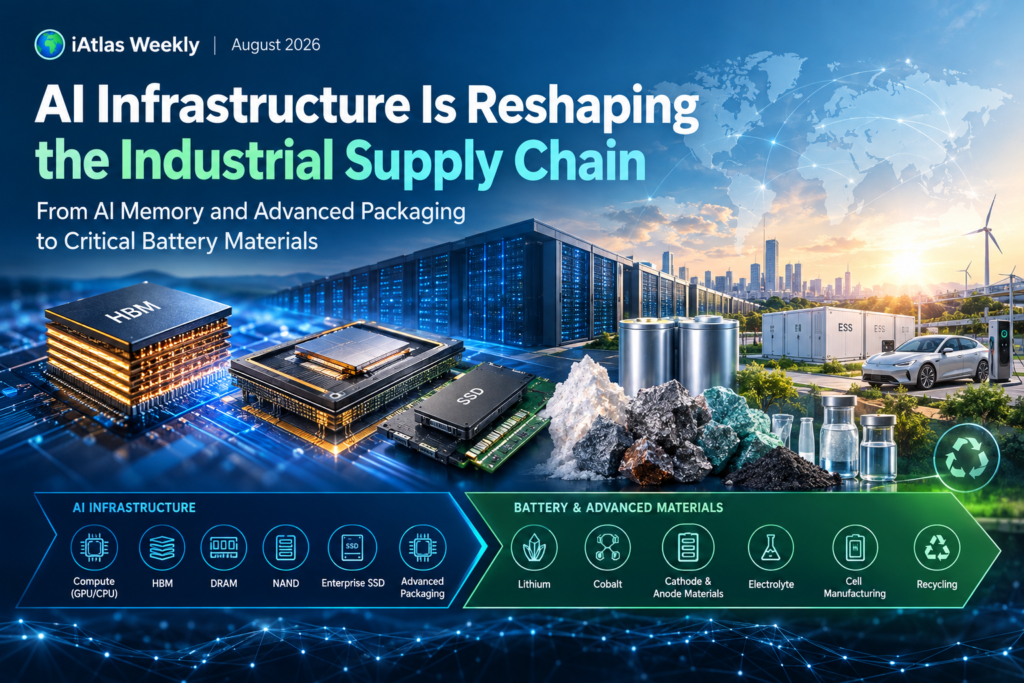
The AI Infrastructure Supply Chain is expanding rapidly as investment moves beyond GPUs and data centers into memory, advanced packaging, storage, power infrastructure and critical materials.
For much of the past two years, the AI story was dominated by GPUs, accelerators, and hyperscale data centers. But the latest developments show that the next phase of competition is spreading far beyond compute chips.
Memory capacity is expanding. Advanced packaging is becoming strategic infrastructure. NAND and enterprise storage are becoming increasingly important to AI systems. At the same time, governments are investing in domestic battery materials and critical-mineral supply chains.
The common thread is becoming increasingly clear:
The next phase of technology competition will depend not only on who designs the best chips or batteries, but on who controls the industrial infrastructure required to manufacture them at scale.
🌎 The Big Picture
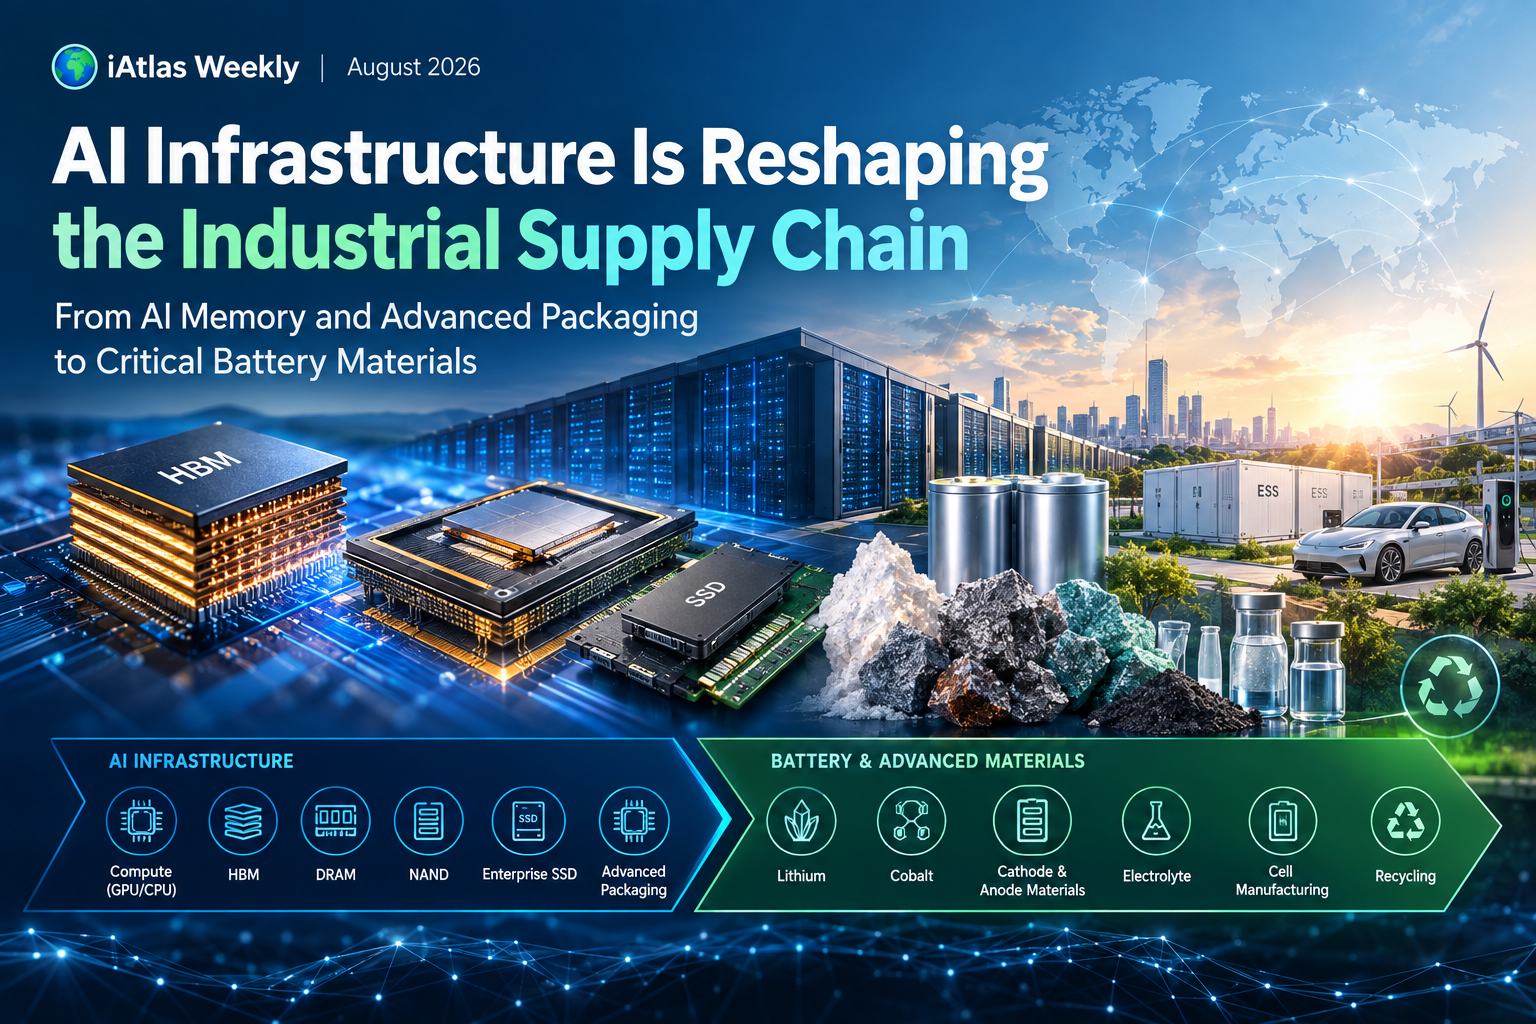
The AI Infrastructure Supply Chain is becoming a much broader industrial ecosystem.
A modern AI data center requires far more than GPUs.
It depends on:
Compute → HBM → DRAM → NAND → Enterprise SSD → Advanced Packaging → Power → Cooling → Networking → Materials
And outside the data center, another strategic infrastructure race is developing around batteries:
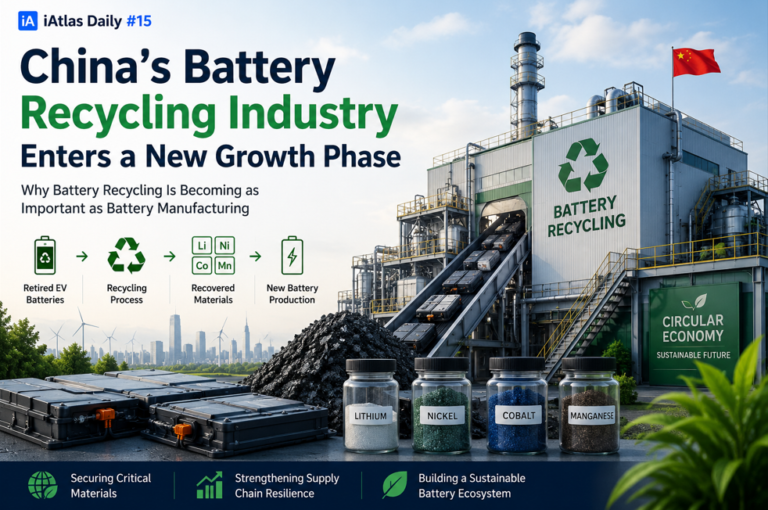
Lithium → Cathode & Anode Materials → Electrolyte → Cell Manufacturing → Recycling
These two supply chains may appear different.
But strategically, they are moving in the same direction:
Localization, capacity expansion, and supply-chain control.
This was one of the clearest themes across this week’s industrial developments.
🧠 1. AI Memory Is Expanding Beyond HBM
HBM has become one of the most important components of the AI semiconductor boom.
But the industry is now looking beyond HBM alone.
SK hynix recently presented a broader portfolio of memory solutions for AI infrastructure, including HBM, DRAM, enterprise SSDs and computational storage. Its recent technology communications also emphasize that AI infrastructure increasingly depends on how efficiently data can be stored, moved and accessed across different memory layers.
This represents an important shift.
The first phase of the AI memory boom could be summarized as:
GPU → HBM
The emerging architecture is much broader:
GPU → HBM → DRAM → NAND → eSSD → Storage Infrastructure
As AI models grow and inference workloads expand, enormous amounts of data must continuously move between compute and storage.
That makes the entire memory hierarchy strategically important.
Why It Matters
For memory manufacturers, AI is therefore becoming more than an HBM opportunity.
It could drive investment across:
- HBM
- server DRAM
- NAND flash
- enterprise SSDs
- computational storage
- advanced packaging
- memory interconnect technologies
The AI memory market is evolving toward a full-stack memory opportunity.
🏭 2. SK hynix Is Localizing the AI Memory Supply Chain
One of the week’s most important developments came from the United States.
SK hynix has broken ground on its approximately $4 billion Indiana project, which is intended to establish advanced HBM packaging and AI semiconductor R&D capabilities in the United States.
The company expects next-generation HBM4E mass production at the site from 2029, while advanced wafers will continue to be manufactured primarily in Korea before being sent to Indiana for packaging and testing.
The significance extends beyond one factory.
It represents a structural change in the semiconductor supply chain.
Traditionally:
Asia → Semiconductor Manufacturing → Packaging → Global Customers
The emerging model increasingly looks like:
Asia Manufacturing + Regional Advanced Packaging + Local AI Customers
Locating advanced packaging closer to major AI customers can shorten development cycles and strengthen cooperation between memory suppliers, accelerator companies and hyperscalers.
SK hynix is simultaneously expanding its Korean manufacturing base, including major investments in Yongin and Cheongju.
Atlas Insight
This suggests that semiconductor localization does not necessarily mean relocating the entire semiconductor supply chain.
Instead, the industry may increasingly develop distributed manufacturing networks:
Korea — advanced memory manufacturing
↓
United States — advanced packaging & R&D
↓
AI customers — system integration
That could become an important model for the next generation of semiconductor globalization.
💾 3. NAND Is Becoming Part of the AI Infrastructure Race
Another important development is occurring in flash memory.
AI systems generate and process enormous amounts of data, creating growing demand for high-performance storage.
This is pushing NAND and enterprise SSDs deeper into the AI infrastructure conversation.
At FMS 2026, several memory companies highlighted storage technologies optimized for AI workloads. SK hynix discussed technologies spanning HBM, NAND and SSDs, while Kioxia showcased PCIe 6.0 NVMe SSD technology designed around next-generation AI infrastructure requirements.
Meanwhile, competition in the global NAND industry is intensifying.
China’s YMTC is pursuing aggressive expansion as it seeks to strengthen its position in the global flash-memory market.
The competitive landscape therefore increasingly includes:
- Samsung Electronics
- SK hynix / Solidigm
- Kioxia
- Micron
- SanDisk
- YMTC
AI demand could make storage a larger strategic battleground than it has been during the GPU-centered phase of the AI boom.
🧩 4. Advanced Packaging Is Becoming Strategic Infrastructure
As semiconductor architectures become more complex, packaging is no longer simply the final manufacturing step.
It is increasingly part of chip architecture itself.
HBM is a good example.
An AI accelerator may combine:
GPU / Accelerator -> HBM stacks -> Interposer -> Advanced package -> AI server
The performance of the final system depends on how efficiently these components communicate.
Technologies such as:
- 2.5D packaging
- 3D packaging
- hybrid bonding
- chiplets
- TSV
- advanced substrates
are therefore becoming increasingly important.
SK hynix’s recent technical work on hybrid bonding reflects this shift, with the company describing the technology as increasingly important for improving semiconductor performance and future HBM development.
This changes the competitive equation.
In the past:
Better transistor technology often meant better semiconductor performance.
Increasingly:
Better system integration can also mean better semiconductor performance.
🔋 5. Battery Competition Is Moving Upstream
The same strategic shift can be seen in the battery industry.
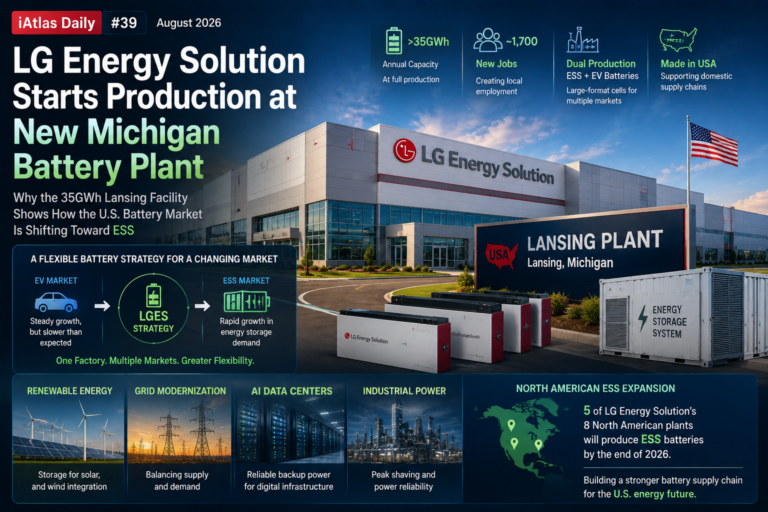
This week, the U.S. Department of Energy announced $500 million for seven selected projects covering critical-mineral processing, battery manufacturing and recycling.
The projects span areas including lithium, cobalt, battery recycling and advanced battery materials.
This matters because battery manufacturing capacity alone does not guarantee battery supply-chain security.
A battery depends on a much longer chain:
Mining -> Mineral Processing -> Cathode / Anode Materials -> Electrolyte & Separator ->
Cell Manufacturing -> Battery Pack -> Recycling
If upstream materials remain concentrated overseas, domestic cell factories can still depend heavily on foreign supply chains.
That is why government policy is increasingly moving upstream.
⛏️6. Critical Minerals Are Becoming Industrial Infrastructure
Lithium and cobalt were once discussed primarily as commodities.
Today, they are increasingly viewed as strategic industrial assets.
The latest U.S. funding program illustrates this shift.
Rather than focusing only on battery factories, support is extending across:
- lithium extraction
- cobalt processing
- advanced anode materials
- electrolyte-related materials
- battery recycling
- domestic processing capacity
The objective is increasingly to build a complete domestic battery ecosystem, rather than simply increase battery-cell production.
This mirrors what is happening in semiconductors.
Semiconductor
Chip Design → Wafer Manufacturing → Memory → Packaging → Equipment → Materials
Battery
Mining → Materials → Cell Manufacturing → Equipment → Recycling
Both industries are moving toward the same strategic objective:
Control more of the supply chain.
⚡ 7. The Real AI Opportunity Is Expanding Beyond Chips
One of the most important lessons from recent industrial developments is that AI infrastructure is becoming a much larger industrial market.
AI data centers require:
Semiconductors
HBM, CPUs, GPUs, networking chips and storage.
Electrical Infrastructure
Transformers, switchgear, UPS systems and power distribution.
Thermal Infrastructure
Liquid cooling, chillers, pumps and heat exchangers.
Networking
Optical transceivers, switches and high-speed interconnects.
Construction & Materials
Steel, copper, cables and specialized facilities.
Energy Storage
Batteries, backup power and grid stabilization systems.
This means AI investment is beginning to influence companies far outside the traditional semiconductor industry.
The AI boom is increasingly becoming an industrial infrastructure boom.
🔭 What to Watch Next
Several developments deserve close attention over the coming months.
1. HBM capacity
AI accelerator demand will continue to drive investment in advanced memory.
2. AI storage
Enterprise SSD and high-performance NAND could emerge as the next major AI memory growth market.
3. Advanced packaging
HBM integration, chiplets and hybrid bonding will become increasingly important manufacturing bottlenecks.
4. U.S. semiconductor localization
The SK hynix Indiana project could provide an important model for combining Asian wafer manufacturing with U.S. advanced packaging.
5. Chinese memory expansion
YMTC and other Chinese memory manufacturers could increasingly influence global NAND competition.
6. Battery material localization
Government incentives will continue moving upstream from battery factories toward minerals, materials and recycling.
🧭 Atlas Insight
The AI Infrastructure Supply Chain is therefore evolving from a semiconductor-centered ecosystem into a much broader network connecting memory, packaging, storage, energy, materials and manufacturing.
The most important industrial trend this week was not one individual investment announcement.
It was the expansion of strategic competition across entire supply chains.
AI started as a semiconductor story.
Then it became an HBM story.
Now it is becoming a:
Memory → Packaging → Storage → Power → Cooling → Infrastructure
story.
Battery manufacturing is following a similar path.
The focus is shifting from:
Battery Cells
to:
Minerals → Materials → Manufacturing → Recycling
The strategic question facing governments and companies is therefore changing.
It is no longer simply:
Who can build the best technology?
Increasingly, the question is:
Who can build and control the industrial ecosystem required to manufacture that technology at scale?
That distinction could define the next phase of competition in semiconductors, AI infrastructure and batteries.
📚 Related Articles
📰 iAtlas Daily #42 – SK hynix Expands AI Memory Beyond HBM
AI memory is evolving from an HBM-centered market toward a broader infrastructure opportunity spanning DRAM, enterprise SSDs and computational storage.
📰 iAtlas Daily #43 – U.S. Battery Materials Supply Chain Gets $500M Boost
Why U.S. industrial policy is moving upstream toward lithium, cobalt, advanced battery materials and recycling.
🔗 Sources
Official Sources
- SK hynix Newsroom — AI Memory & Storage
- SK hynix — From HBM to eSSD
- U.S. Department of Energy — $500 Million Critical Mineral and Battery Supply Chain Program
Industry / News Sources
- Reuters — SK hynix Indiana HBM Project
- Reuters — U.S. Critical Minerals and Battery Projects
- Financial Times — YMTC and the NAND Memory Race
About iAtlas
iAtlas is an independent publication covering batteries, semiconductors, OLED, advanced materials, AI, and global industrial trends.
We transform complex industrial developments into clear, reliable, and easy-to-understand insights.
Whether you’re following today’s industry news or building long-term expertise, iAtlas helps you understand not only what happened, but why it matters.
Technology creates change.
Insight creates opportunity.
— iAtlas