Micro OLED Capacity Is Growing Ahead of the Smart Glasses Market
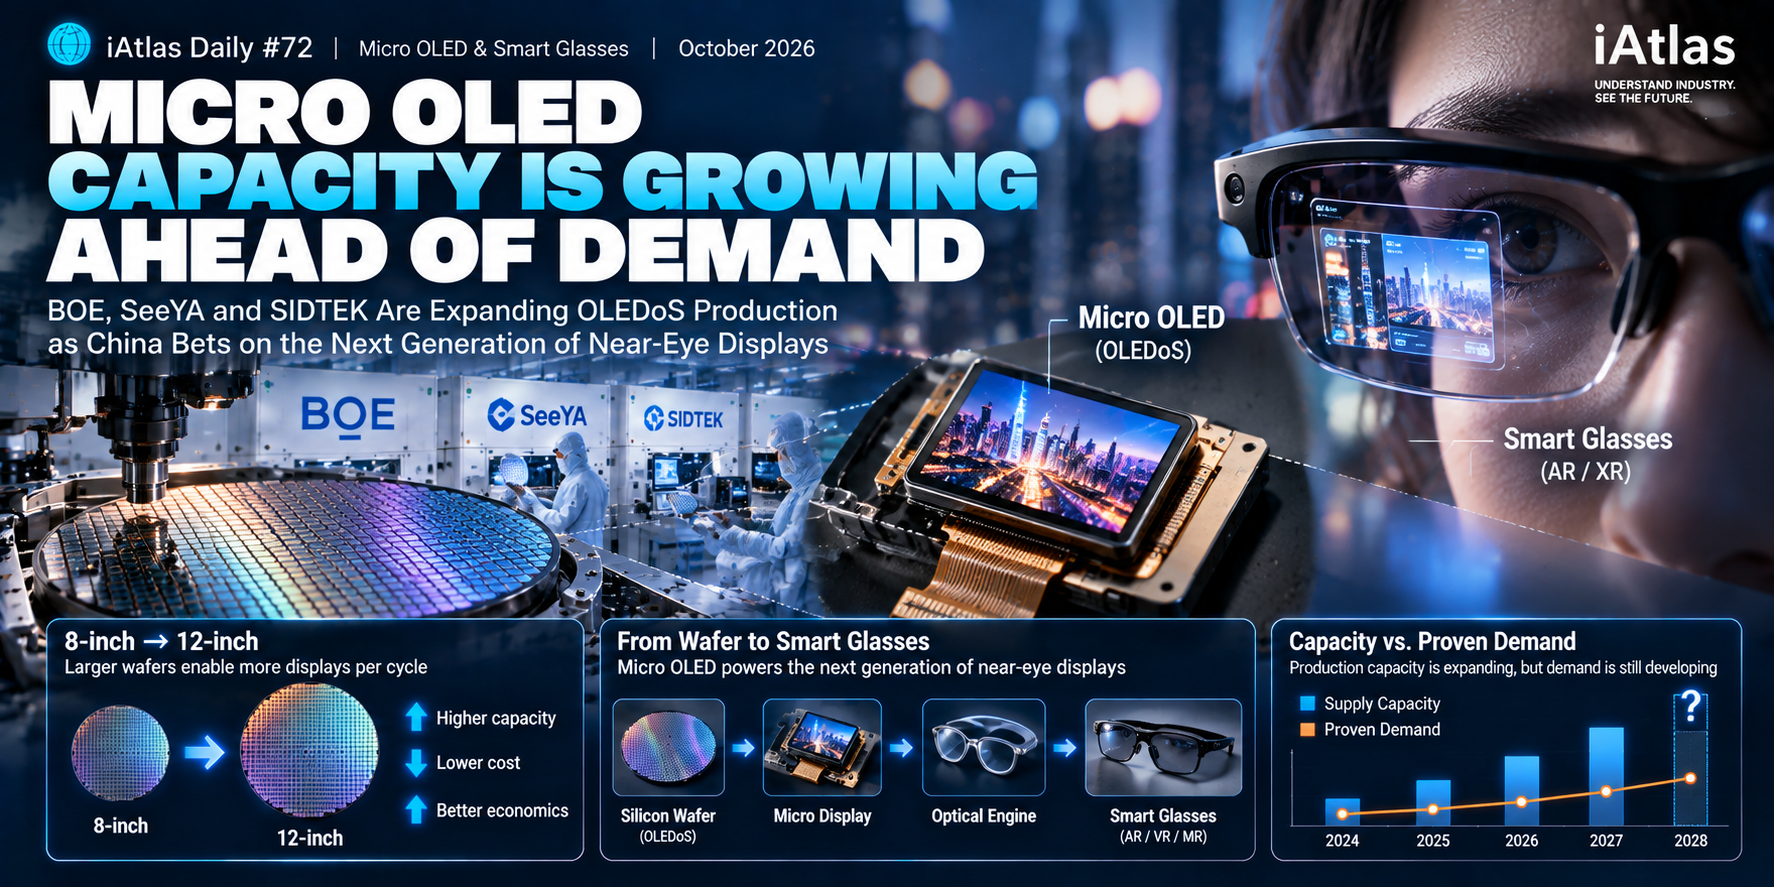
BOE, SeeYA and SIDTEK Are Expanding OLEDoS Production as China Bets on the Next Generation of Near-Eye Displays
🖥️ iAtlas Daily #72 | Micro OLED & Smart Glasses | October 2026
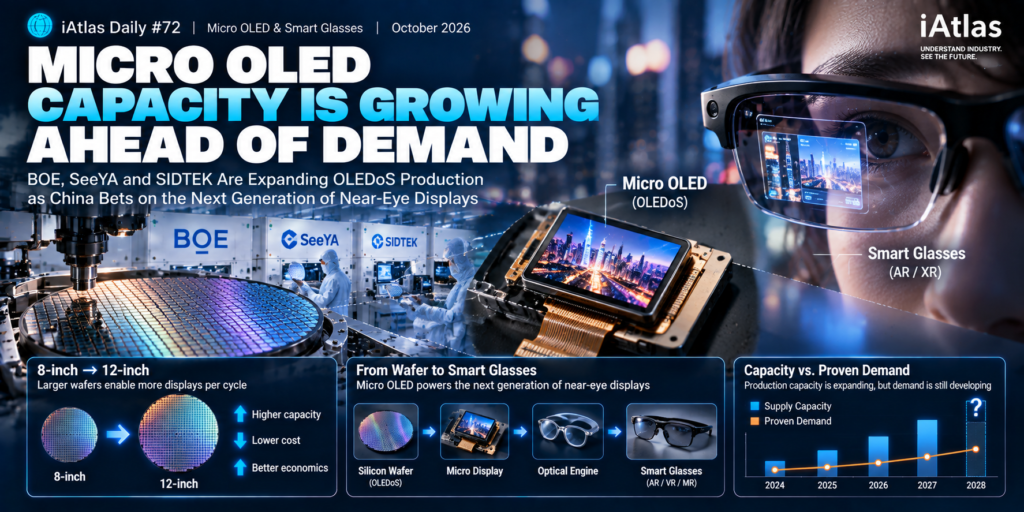
The display inside a pair of smart glasses is tiny.
But the manufacturing investment behind it is becoming much larger.
Across China, display manufacturers are expanding production capacity for:
Micro OLED
also known as:
OLEDoS — OLED on Silicon
Companies including:
BOE
SeeYA Technology
and:
SIDTEK
are building or expanding Micro OLED production as expectations grow around:
AR Glasses
VR / MR Headsets
and:
Spatial Computing
The logic appears straightforward.
Smaller and lighter wearable devices need displays that can deliver:
Very High Pixel Density
High Contrast
Low Power Consumption
and:
High Image Quality
inside an extremely small area.
Micro OLED can provide many of those characteristics.
But there is a catch.
Manufacturing capacity is expanding rapidly.
The consumer market that is supposed to absorb that capacity is still developing.
That creates one of the most important questions facing the emerging microdisplay industry:
Is China preparing early for the next major display market—or building capacity before demand is ready?
🌍 The Big Story
The display industry has seen this pattern before.
A new application emerges.
Manufacturers anticipate rapid growth.
Factories are built.
Capacity expands.
Then the industry discovers whether actual demand matches expectations.
This happened across:
LCD TVs
Smartphones
OLED Smartphones
and:
Large OLED Displays
Now a similar investment cycle may be beginning in:
Microdisplays
But Micro OLED is different from conventional display manufacturing.
The panels are extraordinarily small.
The pixels are extraordinarily dense.
And the technology combines two industrial worlds:
OLED + Semiconductor Manufacturing
That makes Micro OLED particularly interesting for iAtlas.
1. What Is Micro OLED?
Conventional OLED displays typically use a:
Glass
or:
Flexible Substrate
Micro OLED takes a different approach.
The OLED structure is fabricated on:
A Silicon Backplane
This is why the technology is also called:
OLED on Silicon — OLEDoS
The silicon backplane allows extremely small pixels and sophisticated drive circuitry to be integrated underneath the OLED layer.
The result is a display that can be physically tiny while still containing millions of pixels.
2. The Pixel Density Is Extraordinary
Consider a smartphone.
A high-end smartphone display may have pixel density measured in several hundred:
PPI
pixels per inch.
Micro OLED operates at a completely different scale.
BOE, for example, lists Micro OLED products above:
4,000 PPI
and one 0.39-inch product at:
5,644 PPI. Boe
Why does that matter?
Because in near-eye displays, the screen sits extremely close to the user’s eye.
Individual pixels therefore need to become much harder to distinguish.
3. Near-Eye Displays Create a Different Problem
A television can be several meters away.
A smartphone may be tens of centimeters away.
A smart-glasses display sits:
Directly in Front of the Eye
That means conventional display resolution is not enough.
The system needs:
Very Small Pixels
High Resolution
High Contrast
Fast Response
and often:
High Brightness
inside an extremely compact optical system.
Micro OLED is attractive precisely because it combines:
OLED Image Quality
with:
Semiconductor-Level Pixel Density
4. This Is Why OLEDoS Has Become Important for XR
Micro OLED is already used in premium near-eye devices.
Its characteristics make it particularly suitable for:
VR
MR
Video-Oriented AR
and other applications where image quality is critical.
TrendForce expects OLEDoS demand in near-eye displays to grow strongly through the end of the decade, driven by AR, VR and MR devices. TrendForce
The opportunity therefore looks significant.
But opportunity and volume demand are not the same thing.
5. Smart Glasses Are Not One Market
The term:
Smart Glasses
can describe very different products.
Some devices are essentially:
Audio + Camera + AI
with no visual display.
Others provide:
Simple Information Overlays
Others aim to deliver:
Large Virtual Screens
And high-end VR/MR devices attempt:
Immersive Spatial Computing
These products do not necessarily need the same display technology.
That distinction is crucial.
6. Micro OLED Has Strong Competitors
Micro OLED is not the only technology competing for near-eye displays.
Depending on the application, manufacturers can choose among:
Micro OLED
Micro LED
LCoS
and other display architectures.
Each has different advantages.
Micro OLED is particularly strong in:
Resolution
Contrast
Image Quality
and:
Manufacturing Maturity
But other technologies can offer advantages in areas such as:
Brightness
Power
or:
Optical Efficiency
The smart-glasses market may therefore become:
Multi-Technology
rather than converging around one universal display.
7. That Makes Capacity Planning Difficult
Imagine building a large factory for a market that is growing rapidly.
That sounds attractive.
But manufacturers need to know:
Which devices will succeed?
Which display architecture will they use?
What panel size will they require?
How quickly will shipments grow?
and:
What price can customers accept?
Those answers are still evolving.
Yet production capacity needs to be planned years in advance.
This creates a fundamental industrial mismatch:
Factories Move Slowly
while:
Consumer Markets Move Quickly
8. China Is Expanding Anyway
Chinese suppliers are not waiting for every market question to be answered.
BOE, SeeYA and SIDTEK are among the companies expanding Micro OLED manufacturing.
DIGITIMES reported on October 1 that Chinese suppliers are increasing capacity as smart glasses attract greater attention, while industry sources also warn that demand remains uncertain. Digitimes Apps
The strategic logic is understandable.
If smart glasses become a major computing platform, suppliers want manufacturing capacity ready:
Before Demand Explodes
not after.
9. SeeYA Is Scaling Through the Capital Market
SeeYA is one of China’s important OLEDoS manufacturers.
The company moved forward with its STAR Market listing and planned to use approximately:
CNY 2.015 Billion
in raised capital to expand Micro OLED production capacity and its R&D center.
TrendForce sees SeeYA’s expansion as part of the development of a more localized Chinese OLEDoS supply chain alongside companies such as:
BOE
SIDTEK
and:
OLiGHTEK. TrendForce
This is more than capacity expansion.
It is ecosystem formation.
10. SIDTEK Is Moving to 12-Inch Production
One of the most important manufacturing transitions is:
8-inch → 12-inch
SIDTEK has developed both 8-inch and 12-inch Micro OLED manufacturing capability.
Its 12-inch line in Wuhu has reached volume production with reported capacity of approximately:
6,000 wafers per month. LEDinside
Why move to larger wafers?
Because a larger wafer can potentially produce:
More Microdisplays per Process Cycle
That creates an opportunity to reduce unit manufacturing cost.
11. Wafer Size Is Really About Economics
Micro OLED manufacturing shares important characteristics with semiconductor fabrication.
The display is produced on silicon wafers.
If the process moves from:
8-inch
to:
12-inch
the wafer area increases substantially.
That potentially allows more display dies to be manufactured simultaneously.
If yield remains strong, manufacturers can improve:
Throughput
and:
Cost per Display
That matters enormously for consumer electronics.
12. Micro OLED Has Historically Been Expensive
Premium display performance comes with a price.
Micro OLED manufacturing combines:
Semiconductor Backplanes
OLED Deposition
Fine Patterning
Encapsulation
Inspection
and:
Precision Assembly
Yield can be challenging.
And the displays have historically been expensive compared with more conventional alternatives.
That is acceptable for:
Premium Headsets
It becomes much harder for:
Mass-Market Glasses
13. Scale Could Change the Cost Equation
This is where China’s capacity expansion becomes strategically important.
More:
12-inch Production
Higher Utilization
Improved Yield
Supplier Competition
could push:
Micro OLED Cost Down
TrendForce argues that increasing competition among Chinese OLEDoS suppliers could help accelerate adoption in AR, VR and MR devices. TrendForce
In other words:
Demand can create scale.
But:
Scale can also create demand
by making the technology cheaper.
14. This Creates a Chicken-and-Egg Problem
Smart glasses manufacturers want cheaper displays before launching high-volume products.
Display manufacturers want high-volume products before investing heavily in cheaper mass production.
So which comes first?
Low-Cost Display
↓
Mass-Market Smart Glasses
or:
Mass-Market Smart Glasses
↓
Low-Cost Display
China’s strategy appears to be:
Build Capacity First
and attempt to push the cost curve downward.
15. But That Strategy Carries Risk
If demand grows slower than expected, factories may face:
Low Utilization
Low utilization creates a serious manufacturing problem.
The fixed cost of:
Buildings
Equipment
Cleanrooms
and:
Engineering
must be spread across fewer products.
That increases unit cost.
Manufacturers may then cut prices to attract customers.
The result can become:
Excess Capacity
↓
Price Competition
↓
Margin Pressure
This pattern is familiar across the display industry.
16. Display Manufacturing Has a History of Cycles
The panel industry has repeatedly experienced:
Capacity Expansion
↓
Oversupply
↓
Price Declines
↓
Investment Slowdown
↓
Demand Recovery
↓
New Capacity
This is one reason capacity announcements need to be interpreted carefully.
More capacity does not automatically mean:
More Profit
Sometimes it means:
More Competition
17. But Oversupply Can Accelerate Adoption
There is another side to this.
Lower panel prices can hurt suppliers.
But they can benefit:
Device Manufacturers
If Micro OLED becomes significantly cheaper, more companies can incorporate it into products.
That can reduce the retail price of:
AR Glasses
VR Headsets
and:
Portable Display Devices
So oversupply can eventually stimulate demand.
The same price decline that hurts the display maker may help expand the end market.
18. China’s LCD History Shows the Power of Scale
China’s display industry already demonstrated what aggressive manufacturing investment can accomplish.
Over time, Chinese companies built enormous:
LCD Production Capacity
This helped drive panel costs downward and transformed the global competitive structure.
China later expanded aggressively into:
OLED
Now it is investing in:
Micro OLED
Micro LED
and other next-generation display technologies.
The strategic pattern is familiar:
Build Capacity
↓
Improve Yield
↓
Reduce Cost
↓
Expand Market Share
19. But Micro OLED Is Technically Different
Micro OLED is not simply a smaller smartphone OLED panel.
The silicon backplane changes the manufacturing architecture.
This brings display manufacturing closer to:
Semiconductor Manufacturing
The process requires expertise across:
Silicon Wafers
CMOS Backplanes
OLED Deposition
Fine Patterning
Encapsulation
and:
Wafer-Level Processing
That creates a different competitive landscape.
20. Equipment Companies Become Important
Capacity expansion does not only benefit panel manufacturers.
Every new Micro OLED line requires equipment.
Depending on the process, that can include:
Deposition
Lithography
Etch
Cleaning
Inspection
Encapsulation
and:
Wafer Handling
This creates opportunities for equipment suppliers across both:
Display
and:
Semiconductor
manufacturing.
21. Korea Is Already Connected to This Expansion
This is particularly interesting from a Korean industrial perspective.
In March 2026, Korean equipment company Sunic System announced an additional order from SeeYA for Micro OLED mass-production deposition equipment.
The company had already secured other Micro OLED equipment orders earlier in the year, taking its reported 2026 order total above:
KRW 60 Billion
by late March.
So Chinese capacity expansion does not exist in isolation.
It creates demand throughout an international equipment supply chain.
22. The Value Chain Crosses Borders
A Micro OLED panel manufactured in China may rely on:
Chinese Capital
Silicon Processing
Korean Equipment
Japanese Materials
Global Semiconductor Technology
and ultimately:
American or Chinese Device Brands
This illustrates an important iAtlas theme.
Industries may become more localized.
But advanced manufacturing remains:
Deeply Interconnected
23. Smart Glasses Could Become the Smartphone Question Again
Every technology cycle eventually produces a question like:
What comes after the smartphone?
Smart glasses are one candidate.
If computing moves from:
Handheld Screens
to:
Wearable Displays
the display industry could gain an entirely new product category.
That is the upside scenario behind current investment.
A pair of glasses may contain displays much smaller than a smartphone panel.
But if hundreds of millions of devices were eventually produced, the manufacturing opportunity could become enormous.
24. But We Are Not There Yet
This distinction is important.
Smart glasses are receiving significant investment and product activity.
But the market has not yet demonstrated:
Smartphone-Scale Demand
Challenges remain around:
Battery Life
Weight
Heat
Optics
Social Acceptance
Applications
and:
Price
Display technology solves only one part of the product.
A great display does not automatically create a successful smart-glasses market.
25. AI Helps the Story—but Does Not Solve the Hardware
AI is creating new interest in wearable devices.
Voice assistants.
Real-time translation.
Visual recognition.
Contextual information.
These applications make smart glasses more useful.
But AI does not eliminate physical constraints.
The device still needs:
Battery
Processor
Camera
Connectivity
Optics
and potentially:
A Display
All inside something people are willing to wear for hours.
The product challenge remains enormous.
26. This Is Why Display Demand Is Difficult to Forecast
A display supplier can produce an excellent panel.
But demand depends on whether the entire device works.
The chain looks like:
Micro OLED
↓
Optical Engine
↓
Smart Glasses
↓
Useful Applications
↓
Consumer Adoption
If any layer fails, display demand can disappoint.
That makes Micro OLED capacity expansion inherently speculative.
27. Yet Waiting Has Its Own Risk
Suppose smart glasses suddenly become successful.
A supplier without sufficient capacity may miss the market.
New semiconductor-style production capacity cannot be built instantly.
Customers also need:
Qualification
Yield Stability
Supply Reliability
and:
Cost Roadmaps
So suppliers need to prepare:
Before Demand Is Certain
This is the dilemma.
28. The Real Competition Is About Timing
Too early:
Low Utilization
Price Pressure
Financial Burden
Too late:
Capacity Shortage
Lost Customers
Lost Market Share
The winning strategy lies somewhere between them.
That makes Micro OLED not just a technology race.
It is:
A Timing Race
29. China’s Bet Is Becoming Clear
Chinese suppliers appear willing to accept some early capacity risk in exchange for the possibility of establishing:
Manufacturing Scale
Lower Cost
Customer Relationships
and:
Supply-Chain Control
before the smart-glasses market fully develops.
If demand arrives, they are positioned to supply it.
If demand develops slowly, the industry could face a period of intense price competition.
Both outcomes are plausible.
30. That Makes the Next Two Years Important
The key question is no longer whether Micro OLED can produce impressive displays.
It can.
The next question is:
Can Micro OLED Become a Mass-Market Display Platform?
That requires more than resolution.
It requires:
Lower Cost
Higher Yield
Large-Scale Manufacturing
and most importantly:
Products Consumers Actually Want
China is building the manufacturing side of that equation now.
The demand side still needs to prove itself.
🧩 Why This Matters
Micro OLED is moving from a premium niche toward industrial scale.
Chinese manufacturers are expanding production and transitioning toward larger 12-inch wafer platforms.
The technology is well suited to near-eye displays.
OLED-on-silicon enables extremely high pixel density in a very small form factor.
12-inch production could improve economics.
Larger wafers can increase the number of displays processed per cycle and potentially reduce unit costs.
But smart-glasses demand remains uncertain.
Industry sources are already warning that capacity could expand faster than proven demand. Digitimes Apps
Lower prices could accelerate adoption.
Greater supplier competition and scale may reduce one of the major barriers to broader Micro OLED use.
The opportunity extends beyond Chinese panel makers.
Equipment and materials suppliers—including Korean companies—can benefit from new production investment.
🔭 What to Watch
12-Inch Production
Watch how quickly SeeYA, SIDTEK and other manufacturers ramp larger-wafer OLEDoS production and improve yield.
Capacity Utilization
New capacity matters only if customers use it. Utilization rates will be an important indicator of whether demand is keeping pace with investment.
Micro OLED Pricing
Falling panel prices could be one of the strongest catalysts for broader smart-glasses adoption.
Smart Glasses Shipments
The key question is whether the category moves beyond early adopters and specialized applications toward meaningful consumer scale.
Competing Display Technologies
Micro LED and LCoS will continue competing with Micro OLED across different AR and XR applications.
Equipment Orders
Watch deposition, lithography, inspection and other equipment suppliers. Capacity expansion should appear in equipment demand before finished-device shipments reach full scale.
🧭 iAtlas Insight
The display industry is making a familiar bet.
Build before the market fully arrives.
Sometimes that strategy creates enormous advantage.
Capacity is ready.
Costs fall.
Customers arrive.
A new industry scales.
But sometimes capacity grows faster than demand.
Prices collapse.
Utilization falls.
And manufacturers spend years absorbing the excess.
Micro OLED now sits somewhere between those two outcomes.
The technology itself is compelling.
Its combination of:
Tiny Size
Extreme Pixel Density
High Contrast
and:
Semiconductor-Level Integration
makes it one of the strongest candidates for premium near-eye displays.
But technology does not create a market by itself.
The ultimate success of Micro OLED depends on something outside the display factory:
Whether people actually want smart glasses.
China’s display manufacturers are not waiting for the answer.
They are building capacity now.
That makes the next phase of Micro OLED particularly important to watch.
The next display battle may not be about who invents the best microdisplay. It may be about who scales at exactly the right time.
📚 Related Articles
📰 iAtlas Daily #66: OLED Manufacturing Is Moving Beyond the Fine Metal Mask
Both stories show how OLED manufacturing is evolving, but at opposite ends of the market: FLiPP addresses next-generation direct-view OLED production, while Micro OLED combines OLED with silicon manufacturing for near-eye displays.
🔗 References
- DIGITIMES — China Ramps Up Micro OLED Capacity Ahead of Proven Smart Glasses Demand
- TrendForce — Demand for OLEDoS in Near-Eye Displays to Rise Steadily
- TrendForce — The Second Half of the AR Glasses Race Begins
- SIDTEK / TrendForce — 8+12-Inch OLEDoS Production Strategy
- BOE — OLEDoS Technology
ℹ️ About iAtlas
iAtlas is an independent publication covering batteries, semiconductors, OLED, advanced materials, AI, and global industrial trends.
We transform complex industrial developments into clear, reliable, and easy-to-understand insights.
Whether you’re following today’s industry news or building long-term expertise, iAtlas helps you understand not only what happened, but why it matters.
Technology creates change.
Insight creates opportunity.
— iAtlas